Social Security Adjustments: Understanding the Latest 2026 Cost-of-Living Increase for U.S. Beneficiaries
Anúncios
Understanding the intricacies of Social Security benefits is paramount for millions of Americans, especially as they approach or enter retirement. A key component of these benefits is the annual Cost-of-Living Adjustment, or COLA. This adjustment ensures that the purchasing power of Social Security benefits is not eroded by inflation. As we look ahead to 2026, many beneficiaries, future retirees, and financial planners are keenly interested in what the next Social Security COLA will entail. This comprehensive guide will delve into the projected 2026 Social Security COLA, its calculation, historical context, and the broader implications for U.S. beneficiaries.
Anúncios
The Cornerstone of Retirement: What is Social Security COLA?
The Cost-of-Living Adjustment (COLA) is an annual increase in Social Security and Supplemental Security Income (SSI) benefits. Its primary purpose is to counteract the effects of inflation, thereby maintaining the purchasing power of beneficiaries’ income. Without COLA, the fixed income of retirees and other beneficiaries would steadily lose value over time, making it harder to afford essential goods and services.
The concept of COLA was introduced in 1975, following amendments to the Social Security Act in 1972. Before this, benefit increases required an act of Congress. The automatic COLA mechanism was a significant step towards ensuring the financial stability of beneficiaries, linking their income directly to changes in the cost of living.
How is the Social Security COLA Calculated?
The Social Security Administration (SSA) determines the COLA based on the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W). Specifically, the average CPI-W for the third quarter (July, August, and September) of the current year is compared to the average CPI-W for the third quarter of the most recent year in which a COLA was payable. The percentage increase, rounded to the nearest one-tenth of one percent, becomes the COLA for the following year.
Anúncios
For example, to determine the 2026 Social Security COLA, the SSA will compare the average CPI-W for the third quarter of 2025 to the average CPI-W for the third quarter of 2024 (assuming a COLA was payable in 2025). If there is no increase, or if the CPI-W decreases, there is no COLA for that year. This happened in 2010, 2011, and 2016.
It’s important to note that the CPI-W is a specific measure of inflation that tracks the spending habits of urban wage earners and clerical workers. While it serves its intended purpose for COLA calculations, some critics argue that it may not fully reflect the actual spending patterns and healthcare costs faced by seniors, who often have different expenditure profiles than the general working population.
Projecting the 2026 Social Security COLA: What to Expect
Predicting the exact 2026 Social Security COLA this far in advance is inherently challenging, as it depends entirely on future inflation data, specifically the CPI-W readings for July, August, and September of 2025. However, economists and financial analysts often provide projections based on current economic trends, inflation forecasts, and historical data.
Factors Influencing the 2026 COLA
Several key economic indicators will play a significant role in determining the 2026 Social Security COLA:
- Overall Inflation Rates: The general trajectory of inflation, influenced by factors such as energy prices, food costs, and housing, will be the most critical determinant. Persistent high inflation in 2025 would likely lead to a higher COLA in 2026. Conversely, a significant cooling of inflation could result in a lower COLA.
- Energy Prices: Fluctuations in oil and gas prices have a substantial impact on the CPI-W, as transportation and energy costs are significant components of household budgets.
- Food Prices: Staple food items also heavily influence the CPI-W. Supply chain issues, weather events, and global economic conditions can all affect food inflation.
- Wage Growth: While not directly used in the COLA calculation, strong wage growth can sometimes be correlated with higher consumer demand and, subsequently, higher inflation.
- Monetary Policy: The actions of the Federal Reserve, particularly interest rate adjustments, aim to control inflation. The effectiveness of these policies in 2025 will indirectly influence the COLA for 2026.
As of late 2024, early projections for the 2026 Social Security COLA are speculative. However, many analysts anticipate that inflation, while potentially moderating from recent peaks, will likely remain elevated enough to warrant a meaningful COLA. Initial forecasts often range from 2.5% to 3.5%, but these are subject to considerable revision as 2025 progresses and more concrete inflation data becomes available.
Historical Context: A Look Back at Social Security COLA Trends
Understanding past Social Security COLA adjustments can provide valuable insights into what beneficiaries might expect. The history of COLA reflects periods of both high and low inflation, directly impacting the size of the annual increase.
Notable COLA Adjustments:
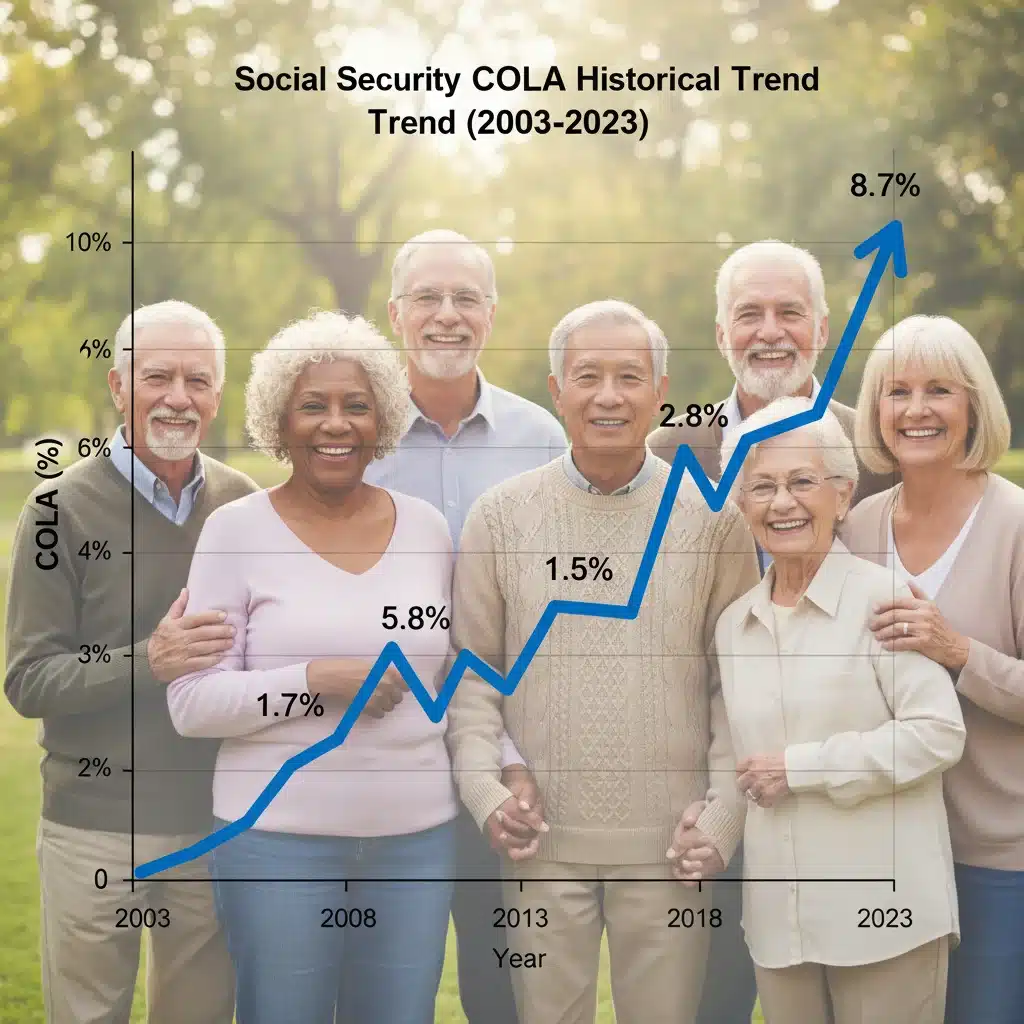
- High COLA Years: The late 1970s and early 1980s saw some of the highest COLA increases due to rampant inflation. For instance, the 1980 COLA was a staggering 14.3%. More recently, the 2022 COLA of 5.9% and the 2023 COLA of 8.7% were significant, reflecting the surge in inflation post-pandemic.
- Low or Zero COLA Years: Conversely, periods of low inflation have resulted in minimal or no COLA. As mentioned, 2010, 2011, and 2016 saw no COLA due to very low or negative inflation as measured by the CPI-W.
These historical trends underscore the direct relationship between inflation and Social Security benefit adjustments. A stable economic environment with moderate inflation typically leads to modest, but consistent, COLA increases, while volatile economic periods can cause more dramatic swings.
Impact on U.S. Beneficiaries: More Than Just a Number
The 2026 Social Security COLA will have far-reaching implications for millions of Americans, including retirees, disabled workers, and survivors. It’s not merely a percentage increase; it’s a critical component of their financial well-being.
Increased Monthly Benefits
The most direct impact of a COLA is an increase in monthly Social Security payments. For someone receiving an average benefit, even a modest percentage increase can translate into hundreds of additional dollars annually, which can be crucial for covering rising living expenses.
Medicare Part B Premiums
An important consideration for many beneficiaries is the interaction between COLA and Medicare Part B premiums. By law, if a beneficiary’s Social Security benefit increases due to COLA, their Part B premium cannot increase by more than the dollar amount of their COLA increase. This ‘hold harmless’ provision protects many beneficiaries from having their net Social Security benefit decrease due to rising Medicare costs. However, this provision doesn’t apply to all beneficiaries, such as those new to Medicare, those who don’t have their Part B premiums deducted from their Social Security benefits, or those with higher incomes subject to IRMAA (Income-Related Monthly Adjustment Amount).
Taxation of Social Security Benefits
Another factor to consider is the taxation of Social Security benefits. As benefits increase with COLA, some beneficiaries may find themselves crossing income thresholds that subject a portion of their Social Security income to federal taxation. Currently, up to 50% or 85% of Social Security benefits can be taxable depending on a beneficiary’s combined income (adjusted gross income + non-taxable interest + half of Social Security benefits). These thresholds are not indexed for inflation, meaning that COLA increases can push more beneficiaries into taxable territory over time, a phenomenon sometimes referred to as ‘bracket creep.’
Financial Planning and Budgeting
For individuals and families relying on Social Security, the COLA is a vital factor in their financial planning and budgeting. A predictable COLA helps in forecasting future income and managing expenses. Financial advisors often incorporate COLA projections into retirement planning models to provide more accurate long-term financial outlooks for their clients.
The Broader Economic Picture and Future Outlook
The 2026 Social Security COLA will not exist in a vacuum. It will be a reflection of the broader economic environment in the U.S. and globally. Understanding this context is essential for a complete picture.
Inflationary Pressures and Global Economy
Global economic stability, supply chain resilience, geopolitical events, and energy market dynamics all contribute to inflationary pressures. Should global conditions remain volatile through 2025, it could lead to continued upward pressure on prices, and consequently, a higher COLA. Conversely, a significant global economic slowdown could dampen inflation and result in a lower COLA.
The Health of the Social Security Trust Funds
While COLA directly addresses the purchasing power of benefits, it also indirectly relates to the long-term solvency of the Social Security trust funds. Higher COLA payments mean larger outflows from the trust funds. The latest Trustees’ Report projects that the Old-Age and Survivors Insurance (OASI) Trust Fund will be able to pay 100% of scheduled benefits until the mid-2030s. After that, it will be able to pay about 80% of scheduled benefits if Congress does not act. While COLA is a necessary adjustment, its size does have implications for the overall financial health of the system.
Policy Debates and Potential Reforms
The method of calculating COLA has been a subject of ongoing debate. Some argue for using a different inflation index, such as the Consumer Price Index for the Elderly (CPI-E), which is specifically designed to track the spending habits of those aged 62 and older. The CPI-E typically shows higher inflation rates for seniors due to their greater expenditure on healthcare. Switching to CPI-E would likely result in higher COLA increases, providing more financial relief to seniors but also increasing the strain on the Social Security trust funds. This remains a significant policy discussion point that could impact future COLA calculations beyond 2026.
Preparing for the 2026 Social Security COLA
While the official 2026 Social Security COLA won’t be announced until October 2025, beneficiaries and those nearing retirement can take proactive steps to prepare:
- Stay Informed: Regularly check reliable sources such as the Social Security Administration’s website, reputable financial news outlets, and economic reports for updates on inflation trends and COLA projections.
- Review Your Budget: Periodically review your household budget to understand where your money is going. This will help you assess how any COLA increase (or lack thereof) will impact your overall financial picture.
- Consult a Financial Advisor: A financial advisor can help you integrate COLA projections into your long-term retirement plan, especially concerning how it interacts with other income sources, investments, and expenses like Medicare premiums.
- Understand Medicare Costs: Be aware of how Medicare Part B and D premiums are determined and how they might interact with your Social Security COLA. This is particularly important for those who may not be covered by the ‘hold harmless’ provision.
- Consider Tax Implications: If your combined income is close to the Social Security taxation thresholds, be mindful that a COLA increase could potentially push more of your benefits into taxable income. Planning for this can help avoid surprises.
Conclusion: Navigating the Future of Social Security Benefits
The 2026 Social Security COLA is a critical adjustment that will help millions of U.S. beneficiaries maintain their purchasing power in the face of inflation. While the exact percentage remains to be seen, it will be a direct reflection of the economic conditions prevailing in 2025, particularly inflation as measured by the CPI-W.
For beneficiaries, understanding how COLA is calculated, its historical context, and its broader implications for their financial planning is essential. It’s more than just an annual percentage; it’s a lifeline that helps bridge the gap between fixed income and rising costs of living. As we move closer to 2026, staying informed and proactively planning will be key to effectively managing the impact of the Social Security COLA on your financial future.
The Social Security system, with its COLA mechanism, aims to provide a degree of financial stability for retirees and other beneficiaries. By keeping a close eye on economic indicators and understanding the mechanics of COLA, individuals can better prepare for the financial landscape of 2026 and beyond, ensuring their golden years are as secure as possible.