Maximizing Social Security Benefits 2026: A Comprehensive Guide
Anúncios
Maximizing Social Security Benefits 2026: A Comprehensive Guide for US Retirees
For millions of Americans, Social Security represents a cornerstone of their retirement income. As we approach 2026, understanding the intricacies of this vital program and developing a strategic approach to claiming your benefits is more crucial than ever. This comprehensive guide is designed to empower US retirees and those nearing retirement with the knowledge and tools needed to maximize social security benefits, ensuring a more financially secure future. We’ll delve into key dates, claiming strategies, spousal and survivor benefits, taxation, and advanced planning considerations, all tailored to the 2026 landscape.
Anúncios
The decisions you make regarding when and how to claim your Social Security can have a profound impact on your lifetime income. A well-informed strategy can mean the difference of tens, or even hundreds, of thousands of dollars over the course of your retirement. Therefore, taking the time to understand the rules, evaluate your personal circumstances, and plan proactively is an investment that truly pays off.
Understanding the Basics of Social Security in 2026
Before we dive into advanced strategies to maximize social security, let’s establish a foundational understanding of how the program works and what changes or considerations might be relevant for 2026. Social Security benefits are calculated based on your highest 35 years of earnings, adjusted for inflation. Your Primary Insurance Amount (PIA) is the benefit you receive if you claim at your Full Retirement Age (FRA).
Anúncios
What is Full Retirement Age (FRA)?
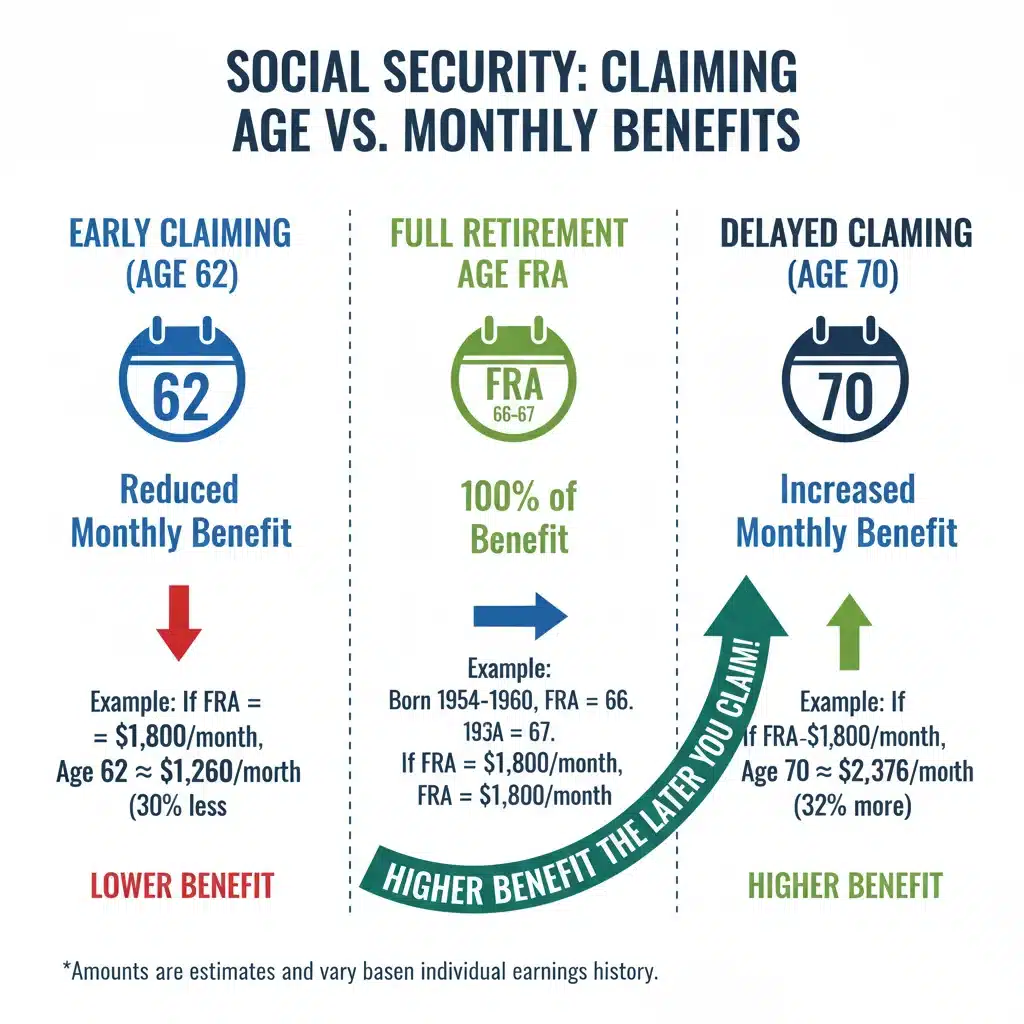
Your Full Retirement Age (FRA) is a critical concept in Social Security planning. It’s the age at which you are entitled to receive 100% of your PIA. For those born in 1960 or later, FRA is 67. If you were born between 1943 and 1959, your FRA falls somewhere between 66 and 67. Claiming benefits before your FRA results in a permanent reduction, while delaying past your FRA can significantly increase your monthly payments.
Cost-of-Living Adjustment (COLA) for 2026
Each year, Social Security benefits are subject to a Cost-of-Living Adjustment (COLA) to help maintain the purchasing power of retirees’ income. While the official COLA for 2026 won’t be announced until late 2025, it’s an important factor to consider in your long-term planning. Historically, COLAs have varied, reflecting inflation rates. A higher COLA can lead to a more substantial increase in your monthly benefit, further emphasizing the importance of maximizing your initial benefit amount.
Earnings Limit Considerations
If you claim Social Security benefits before your FRA and continue to work, your benefits may be reduced if your earnings exceed a certain limit. For 2026, these limits will be announced by the Social Security Administration (SSA). It’s crucial to be aware of these limits if you plan to work while receiving benefits, as exceeding them can temporarily reduce your payments. Once you reach your FRA, the earnings limit no longer applies, and you can earn any amount without your Social Security benefits being reduced.
Strategic Claiming: When to Start Your Benefits to Maximize Social Security
The single most impactful decision you’ll make regarding your Social Security is when to start claiming benefits. This decision is highly personal and should be based on a careful analysis of your health, financial needs, other income sources, and longevity expectations. There are three primary claiming windows: early, at full retirement age, and delayed.
Claiming Early (Age 62)
You can start receiving Social Security benefits as early as age 62. However, claiming early comes with a significant and permanent reduction in your monthly benefit. For someone with an FRA of 67, claiming at 62 results in a reduction of approximately 30%. While this provides income sooner, it means a lower monthly payment for the rest of your life. This option might be suitable for individuals who:
- Have immediate financial needs and no other income sources.
- Are in poor health and do not expect to live a long life.
- Are unable to work due to disability or job loss.
Even in these situations, it’s vital to weigh the short-term gain against the long-term reduction. For many, the reduced benefit can be a significant financial strain over decades of retirement.
Claiming at Full Retirement Age (FRA)
Claiming at your FRA means you receive 100% of your Primary Insurance Amount (PIA). This is often seen as a balanced approach, providing a respectable monthly income without the permanent reductions associated with early claiming. It’s a good option for those who:
- Are in good health and expect to live a reasonable lifespan.
- Have sufficient other retirement savings to bridge the gap if they delay further.
- Wish to retire from work and begin receiving their full earned benefit.
Delaying Benefits (Up to Age 70)
This is often the most powerful strategy to maximize social security benefits for those who can afford to wait. For every year you delay claiming past your FRA, up to age 70, your monthly benefit increases by approximately 8% due to Delayed Retirement Credits (DRCs). This means someone with an FRA of 67 who delays until 70 would receive 124% of their PIA – a substantial and permanent increase. This strategy is ideal for individuals who:
- Are in excellent health and have a family history of longevity.
- Have ample retirement savings or other income sources to cover living expenses until age 70.
- Want to ensure the highest possible guaranteed lifetime income, especially for a surviving spouse.
- Are still working and do not need the income immediately.
The decision to delay can be a game-changer for your financial security, potentially adding hundreds of dollars to your monthly benefit for life.
Spousal and Survivor Benefits: Unlocking Additional Income
Social Security isn’t just about your own work record; it also provides crucial benefits for spouses and survivors. Understanding these provisions is key to a holistic strategy to maximize social security income for your household.
Spousal Benefits
If you are married, you may be eligible to receive spousal benefits based on your spouse’s work record. This is particularly beneficial if one spouse has a significantly higher earnings history than the other. A spouse can receive up to 50% of the higher-earning spouse’s PIA. To claim spousal benefits, your spouse must have already filed for their own benefits. You can claim spousal benefits as early as age 62, but they will be reduced if claimed before your FRA. If you are eligible for both your own benefit and a spousal benefit, the SSA will pay you the higher of the two.
A common strategy to maximize social security for married couples involves one spouse delaying their own benefits to age 70 while the other spouse claims spousal benefits at their FRA. This allows the higher earner’s benefit to grow, providing a larger foundation for future income, while still bringing in some income for the household.
Survivor Benefits
Survivor benefits provide a financial safety net for widows, widowers, and eligible children after a worker’s death. A surviving spouse can receive up to 100% of the deceased worker’s benefit if claimed at their FRA. If claimed earlier, benefits are reduced. It’s important to note that a surviving spouse can claim survivor benefits as early as age 60 (or 50 if disabled). If you are eligible for both your own retirement benefit and a survivor benefit, you can choose to claim one first and switch to the other later if it results in a higher payment. For example, a widow might claim survivor benefits at 60 and then switch to her own (higher) retirement benefit at age 70.
Divorced spouses may also be eligible for spousal or survivor benefits if the marriage lasted at least 10 years and other criteria are met. This often overlooked provision can be a significant source of income for divorced individuals. Consulting with the SSA or a financial advisor is highly recommended to explore these complex rules.
Taxation of Social Security Benefits in 2026
While Social Security benefits provide crucial income, it’s important to be aware that a portion of your benefits may be taxable, depending on your ‘provisional income.’ Provisional income is calculated as your Adjusted Gross Income (AGI) plus non-taxable interest plus one-half of your Social Security benefits.
- Up to 50% of your benefits may be taxable if your provisional income is between $25,000 and $34,000 for an individual, or between $32,000 and $44,000 for a married couple filing jointly.
- Up to 85% of your benefits may be taxable if your provisional income is above $34,000 for an individual, or above $44,000 for a married couple filing jointly.
These thresholds are not indexed for inflation, meaning more retirees may find a portion of their benefits taxable over time as benefits increase with COLA and other income rises. Strategic tax planning, such as managing withdrawals from traditional IRAs versus Roth IRAs, can help manage your provisional income and potentially reduce the taxable portion of your Social Security benefits. This is a critical component of a holistic strategy to maximize social security net income.
Advanced Strategies to Maximize Social Security Benefits
Beyond the basic claiming decisions, several advanced strategies can help specific individuals or couples further optimize their Social Security income.
File and Suspend (No Longer Available for Most)
It’s important to note that the ‘File and Suspend’ strategy, which allowed an individual to file for benefits at FRA and immediately suspend them to earn DRCs while allowing a spouse to claim spousal benefits, was largely eliminated by the Bipartisan Budget Act of 2015. While some very specific grandfathered situations might exist, for most people retiring in 2026, this option is no longer available.
Restricted Application for Spousal Benefits (Limited)
Similarly, the ‘Restricted Application’ strategy, which allowed individuals who reached FRA before January 2, 2016, to file a restricted application for spousal benefits only (while their own benefit continued to grow), is also largely phased out. If you were born on or after January 2, 1954, you cannot use this strategy. For those born before this date, it might still be an option. This highlights the importance of understanding your birth year in relation to these rule changes.
The ‘Do-Over’ Option: Withdrawing Your Application
If you claimed benefits early and later regret your decision, or your financial situation changes, you might have a ‘do-over’ option. You can withdraw your application for Social Security benefits within 12 months of claiming, provided you repay all benefits received. This allows you to restart your benefits at a later date, potentially at a higher amount. This can be a valuable option for those who claimed at 62 but then found themselves able to work longer or realized the impact of the reduced benefit.
Coordinating with Other Retirement Income
Your Social Security strategy should not exist in a vacuum. It must be integrated with your overall retirement income plan, including pensions, 401(k)s, IRAs, and other investments. For example, if you have substantial Roth IRA savings, you might strategically draw from these accounts in your early retirement years to delay claiming Social Security, thereby allowing your benefits to grow. This approach can also help manage your provisional income and reduce Social Security taxation.
Impact of Longevity on Claiming Decisions
One of the biggest unknowns in retirement planning is how long you will live. However, actuarial tables and family health history can provide some guidance. If you anticipate a long lifespan, delaying benefits to age 70 often makes the most financial sense, as the higher monthly payments will compound over many years. Conversely, if health issues suggest a shorter lifespan, claiming earlier might be more appropriate to receive benefits for as long as possible.
Monitoring Your Social Security Statement
Regularly reviewing your Social Security statement is a fundamental step in effective planning. You can access your statement online by creating an account at ssa.gov/myaccount. Your statement provides a detailed record of your earnings history, estimated benefits at different claiming ages, and estimates for spousal and survivor benefits. It’s crucial to check your earnings record for accuracy, as errors can negatively impact your future benefits. If you find discrepancies, contact the SSA immediately to rectify them.
The Role of Professional Advice
Given the complexity of Social Security rules and the significant financial implications of claiming decisions, seeking professional advice is often invaluable. A qualified financial advisor specializing in retirement planning can help you:
- Analyze your personal circumstances, including health, financial resources, and family situation.
- Project your lifetime Social Security income under various claiming scenarios.
- Integrate your Social Security strategy with your overall retirement income and tax plan.
- Navigate complex situations involving spousal benefits, divorce, or disability.
While online calculators can provide estimates, a personalized consultation with an expert can uncover optimal strategies tailored specifically to your needs, helping you truly maximize social security benefits.
Preparing for 2026 and Beyond: Actionable Steps
As you plan for retirement and aim to maximize social security, here are some actionable steps you can take:
- Educate Yourself: Continuously learn about Social Security rules and any potential changes. The SSA website is an excellent resource.
- Create an Online Account: Set up and regularly review your ‘My Social Security’ account at ssa.gov/myaccount to check your earnings record and benefit estimates.
- Assess Your Financial Situation: Understand your current savings, expenses, and other income sources. This will help you determine how long you can afford to delay claiming benefits.
- Consider Your Health and Longevity: Honestly evaluate your health and family history to make an informed decision about claiming age.
- Discuss with Your Spouse: If married, make claiming decisions together, considering spousal and survivor benefits to optimize for the household.
- Consult a Financial Advisor: Work with a professional to develop a personalized Social Security claiming strategy that aligns with your broader retirement goals.
- Stay Informed on COLA: Keep an eye on announcements regarding the Cost-of-Living Adjustment for 2026 and subsequent years.
Conclusion: Secure Your Retirement by Maximizing Social Security
Maximizing your Social Security benefits in 2026 requires careful planning, a thorough understanding of the program’s rules, and often, a strategic approach to claiming. The decisions you make today will resonate throughout your retirement, impacting your financial well-being for decades to come. By understanding your Full Retirement Age, strategically choosing your claiming age, exploring spousal and survivor benefits, considering the tax implications, and coordinating with your other retirement assets, you can significantly enhance your lifetime income from Social Security.
Don’t leave potential benefits on the table. Take control of your retirement future by proactively engaging with your Social Security planning. Whether you choose to claim early, at FRA, or delay until age 70, making an informed decision is the key to a more secure and comfortable retirement. Start your planning today to ensure you maximize social security and build the retirement you’ve worked hard for.