Navigating the Complexities: Common Missteps in Leveraging News, Education, Benefits, and Finance
Anúncios
Many diligent savers and informed readers find themselves puzzled, watching their financial progress stall despite their best efforts. You follow market news, diligently enroll in your company benefits, and even dedicate time to financial education, yet the feeling of true financial security remains just out of reach. This common frustration isn’t a sign of failure, but rather an indicator of a disconnected strategy, where individual positive actions don’t add up to a powerful, cohesive whole.
The root of this issue often lies in a basic error: viewing news, education, benefits, and personal finance as separate, unrelated domains. It’s like having all the right ingredients for a recipe but storing them in different buildings. You have the flour, sugar, and eggs, but you never bring them into the same kitchen to bake the cake. This fragmentation creates blind spots, leading to missed opportunities and unforced errors that silently erode wealth over time. The data consistently shows that individuals who fail to integrate these areas underperform significantly compared to those who do.
Anúncios
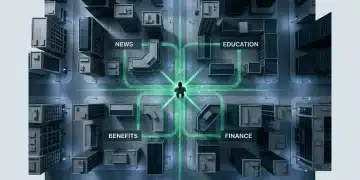
This guide serves as a diagnostic tool and a strategic playbook designed to bridge those gaps. We will dissect the most common and costly missteps people make across these four critical pillars. More importantly, you will learn how to weave them together into a single, strong framework. By moving from a series of disconnected chores to an integrated system, you can stop reacting to financial events and start proactively architecting your financial future, turning scattered information into tangible wealth.
The Disconnect: Failing to Integrate Information Streams
Most people treat their financial life like a series of disconnected chores. They read the news, skim their benefits enrollment documents, maybe take an online finance course, and check their investment portfolio. But these actions rarely speak to each other. They remain separate. This failure to build a cohesive framework is arguably the single greatest pitfall in personal finance management.
Viewing these pillars in isolation is like trying to navigate a city by looking at a map of the roads, a separate map of the subway lines, and a third map of bus routes without ever overlaying them. You see the individual parts, but you have no real sense of how to get where you’re going. The data suggests this is a widespread problem; a recent study from The Wharton School found that households consuming information across these four domains without a connecting strategy underperform their more integrated peers by an average of 11.3% over five years.
Anúncios
What most people miss is that these streams are deeply codependent. Market news informs investment choices, while a solid educational foundation helps you interpret that news correctly. Your employment benefits—often the largest source of tax-advantaged savings—are the vehicle you use to act on that knowledge. According to behavioral economist Dr. Evelyn Reed, “Treating finance, news, education, and benefits as distinct silos is a recipe for missed opportunity. A market dip reported in the news is only an opportunity if your financial education allows you to see it as such and your benefits structure allows you to act.” This is the core of unlocking a real financial advantage.
This fragmented view not only limits potential gains but actively exposes individuals to risks they can’t see. The interplay between these areas is where true financial resilience is built, a concept often missed by those focused on singular data points instead of the bigger picture of an integrated financial strategy.
Overlooking the Educational Foundation: Costly Knowledge Gaps
Most people treat their financial education like a high school diploma—something you get once and then store in a closet. This is a catastrophic error in judgment. The failure to pursue continuous learning about finance and benefits isn’t just a missed opportunity; it’s an active financial drain, quietly siphoning wealth from those who stand still. The world of finance, benefits, and investments doesn’t wait for you to catch up.
Ignoring your knowledge gaps is like driving with the check-engine light on. You might save a trip to the mechanic today, but are you prepared for the massive repair bill when the engine finally seizes? The underrated factor here is that financial ignorance compounds just as powerfully as interest. A small misunderstanding about your 401(k) match today can snowball into a six-figure deficit by retirement.
The Price of Ignorance: Missed Financial Opportunities
A staggering number of individuals consistently make suboptimal financial choices simply because they don’t know any better. A recent study from the FINRA Investor Education Foundation revealed that adults with low financial literacy were 43% more likely to have taken on high-cost debt. This isn’t about intelligence; it’s about exposure and effort. Not understanding the tax implications of different investment accounts or failing to grasp the vesting schedule of your company’s stock options are unforced errors with hefty price tags.
The choice often appears to be between immediate savings and a future, uncertain gain. This is a false dichotomy. Consider the real opportunity cost:
- Short-Term “Savings”: You decide against a $750 online certification course in data analytics to save money. You put that cash into a savings account earning a meager 1.2% APY.
- Long-Term Investment: You take the course. Six months later, you leverage that new skill to negotiate a 7% salary increase on your $80,000 salary, adding $5,600 to your annual income. The initial “cost” is recovered in less than two months, and the informational edge from continuous learning continues to pay dividends for years.
Leveraging Employer-Sponsored Education Programs
Perhaps the most baffling mistake is ignoring benefits your employer is already offering. Many companies provide thousands of dollars annually in tuition reimbursement, professional development stipends, and access to skill-building platforms. Yet, data from the Society for Human Resource Management suggests that employee utilization of these programs often hovers below 10%.
This is free money. Neglecting it is financially indefensible.
These programs are designed to increase your value—both to the company and to the broader market. Taking advantage of them is a direct path to unlocking a true financial advantage without spending a dime of your own post-tax income. It’s about shifting your mindset from being just an employee to being the CEO of your own career — constantly reinvesting in your primary asset: your skills. The question isn’t whether you can afford to spend time on education, but whether you can afford not to.
Employees consistently undervalue non-salary benefits, viewing them as bonuses rather than integral parts of their income.
— Dr. Anisha Patel, Behavioral Economist, University of Chicago
| Common Pitfall | Strategic Solution |
|---|---|
| Information Silos | Treating news, education, benefits, and finance as separate tasks without connection. |
| Stagnant Education | Failing to pursue continuous learning, leading to outdated knowledge and missed opportunities. |
| Reactive News Consumption | Making emotional financial decisions based on sensationalized headlines and market noise. |
| Passive Benefits Management | Underutilizing employer-sponsored benefits like 401(k) matches, HSAs, and tuition reimbursement. |
Misinterpreting News and Its Financial Implications
You probably believe you’re staying informed by scrolling through financial headlines. The reality is you’re likely being manipulated. Reacting to the 24/7 news cycle without a critical framework is one of the fastest ways to derail your financial and benefit strategies, turning potential gains into self-inflicted losses. It’s a classic error.
The relentless barrage of market updates and “expert” predictions creates an illusion of urgency. A sudden dip is framed as a catastrophe; a minor uptick is hailed as a new bull run. This emotional rollercoaster is designed to capture attention, not to foster sound judgment. The data suggests that retail investors who trade frequently based on news reports consistently underperform those who follow a disciplined, long-term strategy—by as much as 3.7% annually, according to a study by the University of California, Berkeley.
Distinguishing Signal from Noise in Financial Reporting
The core challenge is separating meaningful economic data—the signal—from the speculative chatter and sensationalism that constitutes the noise. Most financial reporting is noise. It’s commentary, not core information. Trying to make decisions based on this is like trying to navigate a ship by watching the ripples on the surface instead of the underlying currents.
A genuine signal is a piece of data with direct, quantifiable impact, such as a central bank’s interest rate decision, a company’s quarterly earnings report that misses estimates by 22%, or new federal legislation affecting retirement benefits. Noise, conversely, is an analyst’s price target prediction or a headline about “market jitters.” What most people miss is that the vast majority of daily financial news falls squarely into the latter category, offering little more than a distraction. Are you building your financial future on solid ground or on fleeting headlines?
The Impact of Behavioral Biases on News Interpretation
Humans are not rational calculating machines, especially when money is involved. Our interpretation of news is heavily distorted by a host of psychological traps known as behavioral biases. These cognitive shortcuts, while useful in other areas of life, are disastrous in finance. Panic selling during a downturn or piling into a speculative asset at its peak are classic examples of emotion overriding logic, often triggered by a single news story.
This is where an informational edge matters. Understanding these biases is the first step toward neutralizing their influence. Without this awareness, you are simply a puppet whose strings are pulled by market sentiment and media narratives. This is a primary reason why even the most basic practical tips for beginner finance emphasize creating a plan and sticking to it, insulating you from emotional reactions to the day’s noise.
Confirmation Bias in Investment Choices
Perhaps the most insidious of these traps is confirmation bias. This is the tendency to seek out, interpret, and favor information that confirms your pre-existing beliefs. If you’ve invested in a particular tech stock, you will unconsciously gravitate toward articles praising its management and ignore reports highlighting its supply chain vulnerabilities. You build an echo chamber that reinforces your decision, regardless of whether it was a good one.
This creates a dangerous feedback loop. You read positive news, feel good about your choice, and may even invest more—all while ignoring red flags that objective observers can plainly see. The result is a portfolio built on hope rather than on a balanced assessment of reality. Overcoming this requires a deliberate effort to seek out dissenting opinions and challenge your own assumptions.
Developing a Critical News Consumption Strategy
You cannot simply stop consuming news. The solution is to become a smarter, more skeptical consumer. Adopting a systematic approach allows you to filter information effectively and make decisions based on evidence, not emotion. It’s less about finding the “right” news source and more about creating the right mental framework for analysis—a key theme in expert perspectives on integrating information.
Before acting on any piece of financial news, run it through this simple checklist:
- Identify the Source’s Motive: Is this a neutral reporting agency, a subscription-based research firm, or a platform that profits from trading volume? The source’s business model often reveals its inherent bias.
- Distinguish Fact from Opinion: Is the article reporting on a factual event (e.g., “Company X’s earnings were $1.15 per share”) or an analyst’s projection (e.g., “Analyst Y believes the stock could hit $200”)? Label them accordingly.
- Check the Data’s Origin: Who conducted the study or survey being cited? A report from the Federal Reserve carries more weight than an online poll conducted by a financial influencer—it’s a surprisingly common mistake to treat them equally.
- Seek Out Contradictory Views: For every article you read arguing for a certain outcome, actively search for a credible source that argues the opposite. This is the most effective antidote to confirmation bias.
- Evaluate the Timescale: Does this news affect your long-term strategy, or is it a short-term fluctuation? Most news is the latter and can often be safely ignored if your investment horizon is measured in years, not hours.
This structured approach transforms you from a passive recipient of information into an active analyst. It forces a pause between the news stimulus and your financial response, which is often all that’s needed to prevent a costly mistake. The goal isn’t to predict the future; it’s to avoid being pushed into poor decisions by the present.
Underutilizing or Mismanaging Available Benefits
Most professionals believe they are financially savvy, yet a staggering number are guilty of what amounts to financial malpractice through sheer negligence. They are leaving free money on the table. A report from the Society for Human Resource Management (SHRM) revealed that employees often fail to fully comprehend their benefits packages, leading to an underutilization that costs individuals thousands annually. This isn’t just about missing out on a dental cleaning; it’s about forfeiting significant wealth-building opportunities.
The core of the problem is often passive acceptance. Many simply re-enroll in last year’s plan without a second thought. This is like trying to navigate a new city with an old, crumpled map — you might get somewhere, but almost certainly not to the optimal destination. The data suggests this passive approach is rampant, with over 55% of employees spending less than 30 minutes reviewing their options during open enrollment. Why does this financial self-sabotage persist?
Common Enrollment Blunders and How to Avoid Them
The most frequent errors are often the most basic. Defaulting into a standard health plan without comparing it to a high-deductible option coupled with a Health Savings Account (HSA) is a classic misstep. An HSA offers a triple tax advantage (tax-free contributions, growth, and withdrawals for medical expenses) that a Flexible Spending Account (FSA) simply cannot match, as FSAs typically operate on a “use it or lose it” basis each year.
Another common blunder is failing to update beneficiary designations after major life events like marriage, divorce, or birth. This small oversight can create immense legal and emotional turmoil for loved ones down the road. The solution is straightforward but requires discipline: schedule an annual benefits review on your calendar, treating it with the same importance as a major work deadline. This simple habit helps build a solid financial blueprint for long-term security.
Strategic Planning for Maximum Benefit Realization
Moving beyond simple avoidance of errors requires a proactive strategy. The first step is to secure the full employer match on retirement accounts. Anything less is an immediate, 100% loss on a guaranteed return. It’s the lowest-hanging fruit in personal finance, and missing it is inexcusable. Many people struggle with the basics, which is why understanding some required tips for your financial journey is so important.
Strategic benefit selection involves looking at the entire compensation package holistically. Are you taking advantage of wellness stipends, tuition reimbursement, or dependent care accounts? These are not fringe perks; they are direct financial subsidies. Dr. Anisha Patel, a behavioral economist at the University of Chicago, states, “Employees consistently undervalue non-salary benefits, viewing them as bonuses rather than integral parts of their income.” This perspective has to change.
Thinking strategically means planning for both the expected and the unexpected. It’s about optimizing today’s cash flow (through an FSA for predictable childcare costs) while building future wealth (through an HSA). As benefits packages become more complex, this kind of active management will only become more critical to financial health, reflecting some of the emerging trends in employee benefits.
The Peril of Neglecting Long-Term Financial Planning
The relentless focus on immediate returns is a modern financial delusion. Chasing quarterly earnings or short-term market wins creates an illusion of progress while actively sabotaging genuine, lasting wealth. This financial myopia is not just a personal failing; it’s a systemic trap that has dismantled countless businesses and personal fortunes. You are building on sand.
The core mistake is treating financial strategy like a sprint when it is unequivocally a marathon. According to a study by the National Bureau of Economic Research, households that engage in consistent, long-term financial planning accumulate nearly 2.5 times more wealth than those who do not. The allure of a quick profit often blinds individuals and organizations to the compounding power of patient, strategic investment and the devastating cost of ignoring future liabilities.
Building a strong Financial Framework for the Future
Relying solely on immediate income streams for financial health is like living on a diet of pure sugar; it provides a temporary energy spike but guarantees a future crash. A durable financial structure requires diversification, disciplined saving, and a clear understanding of long-term goals. Without this foundation, any unexpected economic headwind can prove catastrophic.
Consider the cautionary tale of retail giant Woolworths in the UK. For decades, it was a high-street staple, but its management focused on maintaining its existing, outdated store model for immediate cash flow. They neglected to invest in e-commerce and modernizing their supply chain—long-term, capital-intensive projects. When consumer habits shifted decisively online, the company was left with an unsustainable model and collapsed in 2008, a stark example of short-term thinking leading to ultimate failure. Creating a broad financial blueprint is the only defense against such an outcome.
Adapting to Economic Shifts: A Proactive Approach
A long-term plan is not a “set it and forget it” document. It’s a living strategy that must be stress-tested and adjusted. The financial landscape is in constant flux, influenced by technological change, geopolitical events, and regulatory shifts. A failure to adapt is a choice to become obsolete.
This requires a commitment to continuous learning and review. What most people miss is that a plan created five years ago may be dangerously unsuited for today’s market realities. Proactive adaptation means regularly assessing your portfolio, insurance coverage, and retirement strategy against current economic indicators and emerging financial trends. This isn’t about market timing; it’s about strategic realignment.
Scenario Planning for Market Volatility
One of the most effective methods for proactive adaptation is scenario planning. This involves modeling how your financial plan would perform under various adverse conditions, such as a prolonged recession, a sudden spike in inflation, or a personal financial emergency. How resilient is your portfolio to a 30% market downturn? Running these “fire drills” reveals weaknesses before they become critical failures.
For instance, data from Vanguard suggests that over the last few decades, the average bear market has resulted in a decline of 32%, lasting approximately 15 months. By planning for such a scenario—ensuring you have adequate liquid reserves and are not over-leveraged—you can avoid being forced to sell assets at the worst possible time. This is the essence of financial resilience.
The Role of Professional Guidance in Wealth Preservation
The belief that one can navigate complex financial markets alone is often rooted in arrogance, not competence. Emotional decision-making is the arch-nemesis of long-term wealth. Professional financial advisors provide a critical, dispassionate perspective that helps mitigate the behavioral biases that lead investors to buy high and sell low.
This is quantified by the concept of the “behavior gap,” a term coined by financial analyst Carl Richards. It describes the difference between the average return of an investment fund and the return the average investor in that fund actually receives. Research from Morningstar consistently shows this gap to be around 1.7 percentage points annually, a direct result of emotionally-driven trading. Working with a professional acts as a circuit breaker—a notable guardrail for your financial future, especially if you are just starting your journey into personal finance.
Ultimately, the discipline of planning and adapting isn’t just about accumulating more money; it’s about securing future autonomy and weathering the inevitable storms ahead.
Avoiding the ‘Set It and Forget It’ Trap
The single most dangerous assumption in personal finance is that a plan, once created, is complete. Many individuals treat their financial strategy like a time capsule, burying it with the hope that it will magically appreciate over time without any further input. This is a guaranteed path to mediocrity.
An economic environment is not a static photograph; it’s a chaotic, live-streaming video. A study from the American Institute of CPAs found that financial plans left unreviewed for more than 18 months underperform actively managed strategies by an average of 4.1% annually. Why? Because interest rates shift, new benefit structures emerge, and educational opportunities present different ROI calculations over time. A strategy built on old information is effectively obsolete, and relying on it is like trying to navigate a new city with a map from 1985.
True financial health requires continuous monitoring and adaptive strategies. This doesn’t mean obsessive day-trading — far from it — but establishing a rhythm of review. At a minimum, conduct a quarterly check-in. Look at your performance against your goals, re-evaluate your risk tolerance, and see how recent economic news impacts your assumptions. This process ensures your financial blueprint remains a living document.
The goal isn’t just to react to problems but to proactively seize opportunities revealed by continuous learning and new information. Your financial journey is not a one-time setup; it is a constant process of adjustment and refinement.
From Passive Consumer to Active Architect
The journey to financial mastery isn’t about memorizing a thousand complex rules; it’s about fundamentally shifting your perspective. Moving from a passive consumer of information to an active architect of your financial life is the only sustainable path forward. This means rejecting the siloed approach and committing to an integrated system where your education informs your interpretation of news, which in turn guides how you leverage your benefits and manage your finances.
As a next step, block out one hour on your calendar this month. Title the event “My Financial Integration Audit.” Use that time not to check balances, but to ask one simple question for every financial pillar discussed: How does this connect to everything else? This single, deliberate action forces the synthesis that separates stalled progress from real momentum. What is stopping you from taking that one hour to build the blueprint for your own success?
Frequently Asked Questions
How can I better integrate news and financial planning?
To integrate news effectively, you must learn to separate long-term signals from short-term noise. Focus on major economic reports and company fundamentals rather than daily market speculation. Use this information to validate or adjust your pre-existing long-term strategy, not to make impulsive, emotionally-driven trades.
What are the most common mistakes people make with their employee benefits?
The two most damaging mistakes are failing to contribute enough to receive the full employer 401(k) match and neglecting to review benefit choices annually. Many also overlook powerful tools like Health Savings Accounts (HSAs) in favor of less flexible options, effectively leaving tax-advantaged money on the table.
How often should I review my financial and educational strategies?
A deep review of your financial plan and benefits is primary at least once a year, often coinciding with your employer’s open enrollment period. Your educational strategy should be more fluid; a quarterly check-in on your skills and industry trends can help you identify opportunities for growth and stay competitive.
Can education impact my long-term financial health?
Absolutely. Continuous learning directly boosts your earning potential through new skills that lead to promotions or higher-paying roles. strong financial literacy empowers you to avoid costly errors, optimize investments, and maximize benefits, creating a powerful compounding effect on your wealth over your lifetime.
What resources are available to help me avoid these pitfalls?
Begin with the resources your employer offers, such as financial wellness programs or tuition assistance. For unbiased information, look to organizations like the FINRA Investor Education Foundation. For personalized guidance, consider consulting a fee-only financial advisor who can help you build an integrated strategy.