U.S. Real Estate Market Forecast 2026: Predicting Mortgage Rate Shifts and Housing Affordability
The U.S. real estate market is a dynamic and ever-evolving landscape, constantly influenced by a myriad of economic factors, demographic shifts, and global events. As we cast our gaze towards 2026, many homeowners, prospective buyers, and investors are eager to understand what the future holds. The central questions revolve around two critical components: mortgage rates and housing affordability. These two elements are intrinsically linked and often dictate the pace and direction of the market. Understanding the real estate forecast 2026 requires a deep dive into macroeconomic trends, Federal Reserve policies, supply and demand dynamics, and evolving consumer behaviors.
Anúncios
Forecasting the future of real estate is never an exact science, but by analyzing current trajectories and expert predictions, we can build a comprehensive picture of potential scenarios. This article will provide an in-depth look at the anticipated shifts in mortgage rates, explore the persistent challenges and potential improvements in housing affordability, and offer actionable insights for navigating the market in 2026. Whether you’re planning to buy, sell, or invest, a clear understanding of the upcoming market conditions is paramount.
The Economic Backdrop: Influences on the 2026 Real Estate Market
To accurately predict the real estate forecast 2026, we must first consider the broader economic environment. Several key indicators will play a significant role in shaping the housing market:
Anúncios
- Inflation: The trajectory of inflation will be a primary driver of Federal Reserve policy. If inflation continues to moderate towards the Fed’s target, it could pave the way for more accommodative monetary policies. Persistent high inflation, however, would likely keep interest rates elevated.
- Federal Reserve Policy: The Federal Reserve’s decisions on the federal funds rate directly impact mortgage rates. Their dual mandate of maximum employment and price stability will guide their actions, and any shifts in their hawkish or dovish stance will reverberate through the housing market.
- Job Market Strength: A robust job market, characterized by low unemployment and wage growth, typically supports housing demand. However, if wage growth outpaces productivity, it could fuel inflation, leading to higher rates.
- Economic Growth (GDP): The overall health of the economy, as measured by GDP, influences consumer confidence and their ability to purchase homes. A strong, stable economy generally bodes well for real estate.
- Global Economic Factors: Geopolitical events, international trade relations, and global economic slowdowns or booms can indirectly affect the U.S. market by influencing investor sentiment and capital flows.
These interconnected factors create a complex web of influences that make precise predictions challenging. However, by understanding their interplay, we can better anticipate the likely direction of the market in 2026.
Mortgage Rate Shifts: What to Expect by 2026
Mortgage rates have been a central point of discussion and concern for potential homebuyers over the past few years. The dramatic increases seen recently have significantly impacted affordability. Looking ahead to the real estate forecast 2026, understanding the potential trajectory of mortgage rates is crucial.
Factors Driving Mortgage Rates
Mortgage rates, particularly for 30-year fixed-rate mortgages, are primarily influenced by:
- The Federal Funds Rate: While not directly tied, changes in the federal funds rate set by the Federal Reserve often lead to corresponding movements in other interest rates, including those for mortgages.
- Inflation Expectations: Lenders price mortgages based on their expectations of future inflation. If they anticipate higher inflation, they will demand higher rates to ensure their returns aren’t eroded.
- Bond Market Performance: Mortgage rates often track the yields on 10-year U.S. Treasury bonds. When bond yields rise, mortgage rates tend to follow suit.
- Economic Growth and Stability: A strong economy can lead to higher demand for credit, pushing rates up. Conversely, economic slowdowns or uncertainties can sometimes lead to lower rates as investors seek safer assets like bonds.
- Supply and Demand for Mortgage-Backed Securities (MBS): The market for MBS, which package individual mortgages into tradable securities, also plays a role. Demand for MBS influences their pricing, which in turn affects mortgage rates.
Expert Predictions for 2026 Mortgage Rates
While forecasts vary, a general consensus among many economists and housing market analysts suggests a potential easing of mortgage rates by 2026 compared to recent peaks. The expectation is that as inflation continues to cool and the Federal Reserve potentially shifts towards a more neutral monetary policy, the upward pressure on rates will diminish. However, a return to the ultra-low rates seen during the pandemic is highly unlikely.
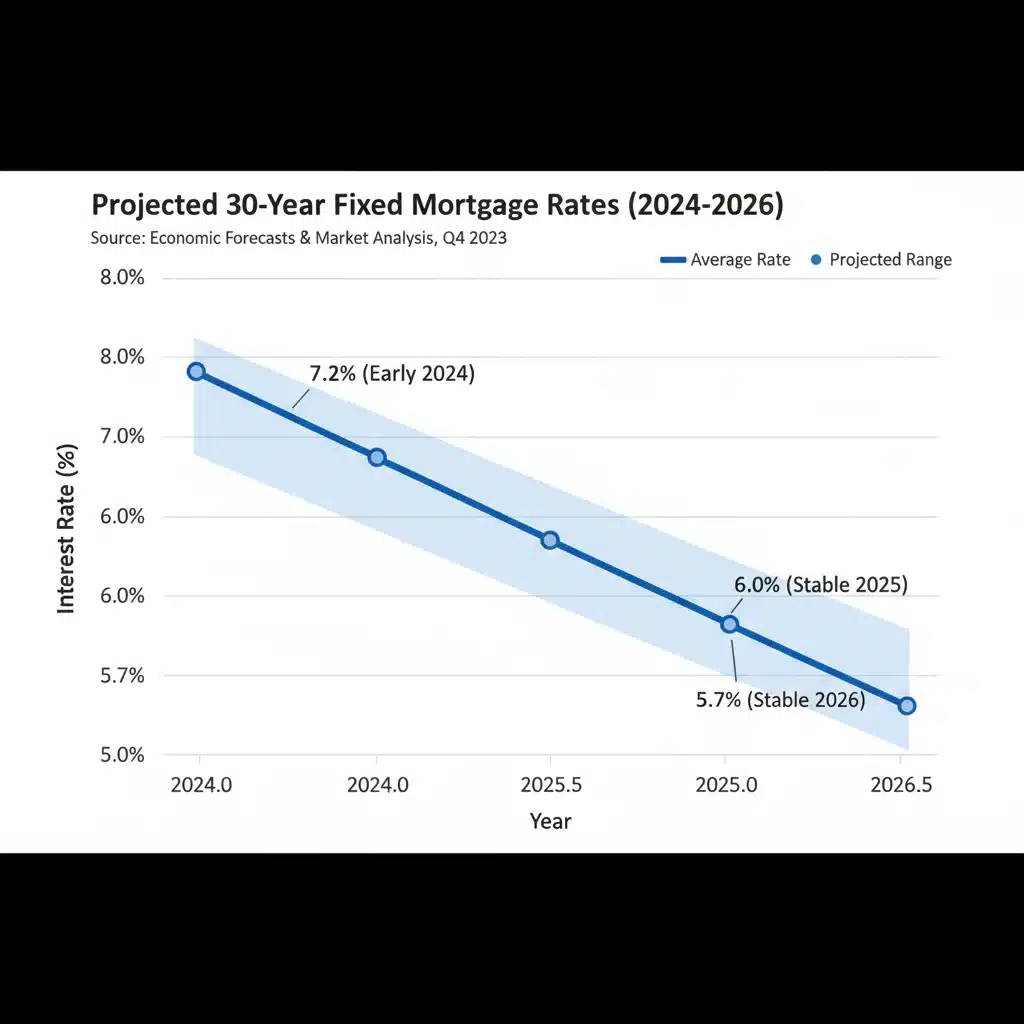
Many predict that 30-year fixed mortgage rates could settle into a range of 5.5% to 6.5% by 2026. This range, while still higher than the historical lows, would represent a significant improvement from the 7% and 8% rates experienced in recent periods. This moderation would offer some relief to homebuyers, making monthly payments more manageable and potentially stimulating demand.
It’s important to note that these are broad predictions. Unforeseen economic shocks, changes in geopolitical stability, or unexpected shifts in inflation could all alter this outlook. Potential homebuyers should monitor these economic indicators closely and consider locking in rates when favorable conditions emerge.
Housing Affordability in 2026: A Persistent Challenge
Housing affordability has been a critical concern across the U.S. for several years, driven by a combination of high home prices, elevated mortgage rates, and stagnant wage growth relative to housing costs. The real estate forecast 2026 indicates that while some improvements might occur, affordability will likely remain a significant challenge for many Americans.
Key Drivers of Affordability Challenges
- High Home Prices: Despite some recent cooling in certain markets, overall home prices remain historically high. A persistent shortage of housing supply, particularly in desirable urban and suburban areas, continues to underpin these elevated values.
- Mortgage Rates: As discussed, higher mortgage rates directly translate to higher monthly payments, reducing a buyer’s purchasing power even if home prices stabilize or slightly decrease.
- Limited Inventory: The fundamental issue of insufficient housing supply continues to plague the market. Years of underbuilding, coupled with homeowners reluctant to sell their current homes with low-interest mortgages, exacerbate the inventory crunch. This imbalance between supply and demand keeps prices firm.
- Wage Stagnation: For many households, wage growth has not kept pace with the rapid escalation in housing costs, widening the gap between income and the ability to afford a home.
- Inflationary Pressures: Increased costs for building materials, labor, and land contribute to higher construction costs, which are then passed on to buyers in the form of higher home prices.
Potential Improvements and Lingering Obstacles
By 2026, some factors could offer a glimmer of hope for improved affordability:
- Moderating Mortgage Rates: As predicted, a decline in mortgage rates would reduce monthly housing costs, making homeownership more accessible for some.
- Increased Housing Supply: Efforts to boost housing construction, including zoning reforms and incentives for builders, could slowly start to bear fruit. However, significant increases in supply typically take time to materialize.
- Market Corrections: In some overheated markets, there might be further price corrections, bringing home values more in line with local incomes. However, widespread, significant price drops are not widely anticipated due to underlying demand and supply constraints.
- Innovative Housing Solutions: The rise of accessory dwelling units (ADUs), smaller homes, and other alternative housing models could offer more affordable options in certain regions.
Despite these potential improvements, significant obstacles will likely persist. The fundamental imbalance between housing supply and demand, particularly for entry-level homes, will continue to exert upward pressure on prices. Furthermore, the cost of land and construction materials, coupled with labor shortages, will likely keep new home prices elevated. Therefore, while affordability might improve marginally in some areas, it will remain a central challenge in the real estate forecast 2026, requiring innovative solutions and sustained policy efforts.
Regional Market Variations in 2026
It’s crucial to remember that the U.S. real estate market is not a monolith. Conditions can vary dramatically from one region to another, and this trend will undoubtedly continue into the real estate forecast 2026. Factors like local job growth, population migration, state-specific housing policies, and economic diversification will play a significant role in how individual markets perform.
Areas to Watch:
- Sun Belt States: Regions in the Sun Belt, particularly those with strong job markets and continued population growth (e.g., Texas, Florida, parts of North Carolina), may continue to see robust demand, potentially sustaining higher price growth, albeit at a slower pace than recent years. However, these areas might also experience more pronounced affordability challenges if supply doesn’t keep up.
- Midwest: Some Midwest markets with lower median home prices and growing tech or manufacturing sectors could offer more stable and relatively affordable options, potentially attracting buyers seeking better value.
- Coastal Metros: Major coastal cities, which have historically high prices, may continue to face significant affordability hurdles. While some may see price adjustments, the underlying demand from high-income earners and limited land availability will likely keep them among the most expensive places to live.
- Remote Work Hubs: The lasting impact of remote work could continue to shape migration patterns. Smaller cities and suburban areas that offer a good quality of life and proximity to amenities, without the astronomical costs of major metros, could see sustained interest.
Investors and homebuyers should conduct thorough local market research, understanding the specific economic drivers and housing dynamics of their target regions. A national forecast provides a general framework, but local nuances will dictate individual experiences in the real estate forecast 2026.
The Role of Technology and Demographics in 2026
Beyond economic indicators, two other powerful forces will continue to shape the real estate forecast 2026: technological advancements and demographic shifts.
Technological Impact:
Technology is rapidly transforming how we buy, sell, and manage real estate:
- AI and Data Analytics: Artificial intelligence and big data will become even more sophisticated in predicting market trends, valuing properties, and personalizing the home search experience.
- Virtual and Augmented Reality: Virtual tours and augmented reality tools will continue to improve, allowing buyers to experience properties remotely with greater immersion and detail, potentially expanding market reach.
- Blockchain Technology: While still nascent, blockchain could streamline transactions, improve transparency, and reduce costs in real estate by simplifying title transfers and property records.
- Smart Home Integration: Homes equipped with advanced smart technology will become more standard, influencing buyer preferences and property values.
- PropTech Innovations: The broader PropTech (Property Technology) sector will continue to introduce new tools for everything from property management to construction, potentially increasing efficiency and reducing some costs over time.
Demographic Shifts:
The changing composition of the U.S. population will also significantly influence the housing market:
- Millennials and Gen Z: These generations will continue to be a dominant force in the housing market. As more millennials enter their prime homebuying years, and Gen Z begins to form households, their preferences for location, home features, and affordability will drive demand. Their comfort with technology will also accelerate the adoption of PropTech.
- Aging Population: The increasing number of retirees will fuel demand for age-restricted communities, accessible housing, and properties that support aging in place. This demographic may also contribute to inventory as some downsizers sell larger family homes.
- Household Formation: The rate of new household formation, influenced by economic conditions and social trends, directly impacts overall housing demand.
- Migration Patterns: As mentioned, migration patterns driven by remote work, climate concerns, and affordability will continue to redistribute demand across different regions.
These technological and demographic trends are not just tangential; they are fundamental drivers that will interact with economic factors to define the character of the real estate forecast 2026.
Strategies for Navigating the 2026 Real Estate Market
Given the anticipated conditions for the real estate forecast 2026, what strategies should buyers, sellers, and investors consider?
For Homebuyers:
- Prepare Your Finances: Focus on strengthening your credit score, saving for a substantial down payment, and getting pre-approved for a mortgage to understand your budget.
- Be Patient and Flexible: The market may still be competitive in desirable areas. Be prepared to act quickly but also be patient for the right opportunity. Consider being flexible on location or home features to find an affordable option.
- Explore All Financing Options: Research different mortgage products, including adjustable-rate mortgages (ARMs) if appropriate for your financial situation, or government-backed loans (FHA, VA, USDA) that may offer more favorable terms.
- Consider a ‘Starter Home’: Instead of waiting for the ‘perfect’ home, consider purchasing a more affordable starter home to get a foot in the door, building equity while you wait for better conditions or more income.
- Work with a Knowledgeable Agent: A local real estate agent with expertise in your target market can provide invaluable insights into specific neighborhood trends, pricing, and negotiation strategies.
For Home Sellers:
- Price Strategically: While demand may remain strong, the days of bidding wars on every property might be less common. Price your home competitively based on comparable sales and current market conditions.
- Focus on Presentation: Invest in staging, minor repairs, and curb appeal to make your home stand out in a potentially more balanced market.
- Understand Your Local Market: Work with an agent who can provide a detailed analysis of your specific neighborhood’s trends, including average days on market and recent sale prices.
- Be Prepared for Negotiation: Sellers might need to be more open to negotiations on price, contingencies, or closing costs than in recent years.
- Highlight Energy Efficiency and Smart Home Features: Buyers are increasingly valuing homes that offer lower utility costs and integrated technology.
For Real Estate Investors:
- Identify Growth Markets: Focus on regions with strong job growth, positive migration trends, and diversified economies that can sustain rental demand and property value appreciation.
- Analyze Rental Yields: With potentially higher interest rates, ensuring a solid rental yield is crucial for cash flow. Research local rental markets thoroughly.
- Consider Different Property Types: Explore opportunities in multifamily properties, build-to-rent communities, or specialized niches like senior housing, which may offer different risk/reward profiles.
- Long-Term Perspective: Real estate is generally a long-term investment. Focus on properties with strong fundamentals that are likely to appreciate over a 5-10 year horizon, rather than short-term gains.
- Diversify Your Portfolio: Don’t put all your eggs in one basket. Consider diversifying across different property types or geographical locations to mitigate risk.
Conclusion: A Cautiously Optimistic Outlook for 2026
The real estate forecast 2026 presents a landscape that is likely to be more balanced than the frenzied markets of the early 2020s, yet still challenging in terms of affordability. We anticipate a moderation in mortgage rates, likely settling into a more sustainable range, which should offer some relief to prospective buyers. However, the underlying issue of housing supply shortages, coupled with persistent demand from a large demographic cohort, means that home prices are unlikely to see widespread, significant declines. Instead, we can expect more modest appreciation in many areas, with some corrections in previously overheated markets.
Housing affordability will remain a key concern, requiring continued innovation in housing policy, construction methods, and financial products. Regional variations will be pronounced, underscoring the importance of localized market analysis. Technological advancements will continue to streamline processes and offer new ways to engage with the market, while demographic shifts will dictate demand for different types of housing.
For those looking to enter or navigate the U.S. real estate market in 2026, the key will be informed decision-making, financial preparedness, and a willingness to adapt to evolving conditions. While the market may not be as easy to navigate as in previous decades, opportunities will undoubtedly exist for those who are well-prepared and strategic. By staying abreast of economic trends, understanding local market dynamics, and leveraging expert advice, individuals can successfully achieve their real estate goals in the years to come.