Navigating 2026 IRS Audit Triggers: What US Taxpayers Must Know Now
Anúncios
Understanding the New 2026 IRS Audit Triggers: What US Taxpayers Should Know Now
As we approach the mid-2020s, the Internal Revenue Service (IRS) continues to evolve its enforcement strategies, technological capabilities, and focus areas. For US taxpayers, staying informed about these changes is not merely advisable; it’s a critical component of sound financial planning and risk mitigation. The year 2026, in particular, is shaping up to be a pivotal point, with new regulations, increased data analytics, and shifting IRS priorities potentially leading to a fresh set of IRS audit triggers. This comprehensive guide aims to shed light on what these new triggers might be, how they differ from past years, and, most importantly, what proactive steps you can take now to safeguard your financial well-being and ensure tax compliance.
The specter of an IRS audit can be daunting for even the most meticulous taxpayer. It conjures images of endless paperwork, stressful interviews, and potentially significant financial penalties. However, understanding the IRS’s approach and recognizing common red flags can significantly reduce anxiety and help you navigate the complex world of tax regulations. Our discussion will delve into the anticipated shifts in IRS enforcement, examining how legislative changes, technological advancements, and economic factors are shaping the agency’s audit landscape. We’ll explore specific areas of increased scrutiny, from cryptocurrency transactions to complex business structures, and provide actionable advice to help you prepare for the future.
Anúncios
The Evolving IRS Landscape: Why 2026 is Different
The IRS is not a static entity. It is continually adapting to new economic realities, legislative mandates, and technological innovations. The period leading up to and including 2026 is marked by several significant developments that are likely to influence its audit activities:
Increased Funding and Enhanced Enforcement
One of the most impactful changes stems from recent legislative actions that have provided the IRS with substantial additional funding. This infusion of capital is earmarked for various purposes, including modernizing archaic IT systems, improving taxpayer services, and, crucially, enhancing enforcement capabilities. A better-funded IRS means more resources for hiring and training auditors, investing in advanced data analytics tools, and pursuing complex cases that might have been overlooked in the past due to resource constraints. This increased capacity directly translates to a higher likelihood of audits for certain taxpayer segments.
Anúncios
Technological Advancements and Data Analytics
The IRS is increasingly leveraging big data and artificial intelligence to identify discrepancies and potential non-compliance. Sophisticated algorithms can now cross-reference vast amounts of data from various sources – including financial institutions, payment processors, and even social media – to flag inconsistencies in tax returns. This means that traditional methods of hiding income or exaggerating deductions are becoming exponentially riskier. The ability of the IRS to connect disparate data points will be a significant factor in determining future IRS audit triggers.
Focus on High-Income Earners and Complex Structures
There has been a clear policy shift towards increasing audit rates for high-income individuals, large corporations, and complex partnerships. This focus is driven by the belief that these segments often have more opportunities for sophisticated tax avoidance schemes and that auditing them yields a higher return on investment for the agency. Taxpayers with significant wealth, intricate business holdings, or international income streams should be particularly vigilant.
New Reporting Requirements
Changes in reporting requirements, such as those related to third-party payment networks (e.g., Venmo, PayPal, Square) and cryptocurrency exchanges, are also playing a role. While some of these changes have seen implementation delays or adjustments, the underlying intent to capture more transactional data remains. Understanding these new reporting thresholds and ensuring all income is accurately reported will be paramount to avoiding future IRS audit triggers.
Anticipated 2026 IRS Audit Triggers: What to Watch For
Based on the evolving landscape, here are some of the key areas that are likely to become significant IRS audit triggers by 2026:
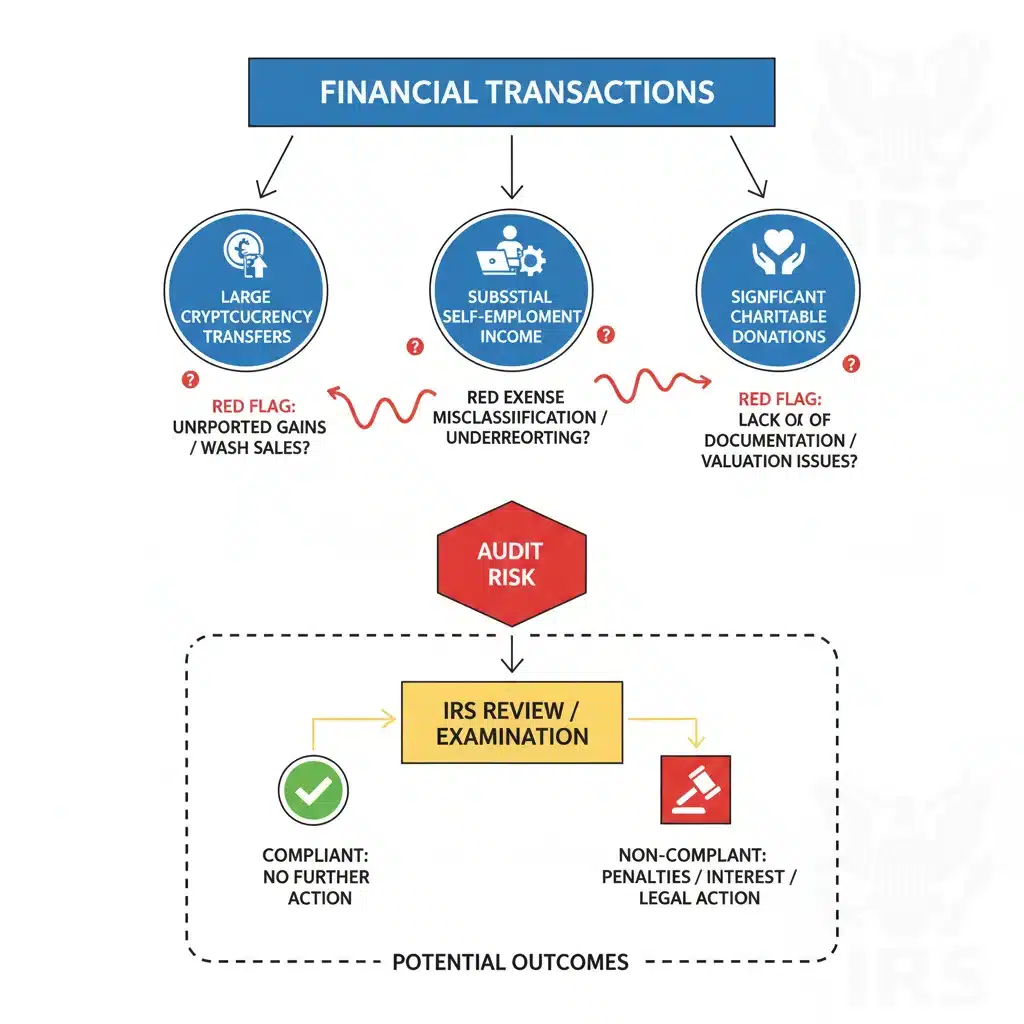
1. Cryptocurrency Transactions and Digital Assets
The IRS has made it abundantly clear that virtual currency is a high-priority area. With the increasing mainstream adoption of cryptocurrencies, NFTs, and other digital assets, the agency has been working to understand and regulate this space. Expect a heightened focus on:
- Unreported Income: Failure to report gains from the sale or exchange of cryptocurrency.
- Inaccurate Cost Basis: Incorrectly calculating the cost basis of digital assets, leading to underreported capital gains.
- Staking and Mining Income: Not reporting income derived from staking, mining, or other decentralized finance (DeFi) activities.
- Large Transactions: Significant transfers or sales of crypto that might be flagged by exchanges reporting to the IRS.
The IRS’s ability to obtain data from crypto exchanges, both domestically and internationally, is improving, making it harder to conceal these activities.
2. High-Income Discrepancies and Lifestyle Audits
For high-income individuals, the IRS will increasingly scrutinize discrepancies between reported income and apparent lifestyle. If your tax return shows modest income but public records, social media, or other data sources suggest a lavish lifestyle (e.g., luxury asset purchases, extensive travel, high-value real estate), it could raise a red flag. This isn’t a direct audit trigger in itself but can be a factor that prompts a deeper look into your financial affairs.
3. Self-Employment and Gig Economy Income
The gig economy continues to expand, and with it, the potential for underreported income. The IRS is enhancing its efforts to track income from platforms like Uber, Airbnb, Etsy, and various freelance marketplaces. While the $600 reporting threshold for 1099-K forms has seen some back-and-forth, the general direction is towards greater transparency. Self-employed individuals and gig workers should:
- Maintain Meticulous Records: Document all income and expenses.
- Accurately Report All Income: Even small amounts can add up and trigger scrutiny if not reported.
- Understand Business Deductions: Claim legitimate business expenses but avoid aggressive or unsubstantiated deductions.
4. Aggressive Business Deductions and Losses
Businesses, especially small businesses and those structured as pass-through entities (S-corps, partnerships), are often fertile ground for aggressive tax planning. The IRS will continue to target:
- Unusually High Deductions: Expenses that seem disproportionate to the business’s income or industry norms.
- Repeated Business Losses: Consistently reporting losses, particularly for businesses that appear to be hobbies rather than profit-seeking ventures.
- Home Office Deductions: While legitimate, these are often scrutinized for proper qualification and calculation.
- Vehicle Expenses: Misuse of personal vehicles for business or inflated mileage claims.
- Meals and Entertainment: Often a target for review, especially if not adequately documented.
5. Foreign Income and Assets (FATCA/FBAR)
The IRS remains intensely focused on international tax compliance. The Foreign Account Tax Compliance Act (FATCA) and the Report of Foreign Bank and Financial Accounts (FBAR) requirements are powerful tools. Failure to report foreign bank accounts, financial assets, or income can lead to severe penalties. With improved international data exchange agreements, hiding foreign assets is becoming increasingly difficult. Taxpayers with international connections should ensure full compliance with all reporting obligations.
6. Large Charitable Contributions
While the IRS encourages charitable giving, unusually large non-cash contributions, especially those involving complex valuation, can be an IRS audit trigger. This includes donations of art, real estate, or other illiquid assets. Ensure you have proper appraisals and documentation to substantiate the value of your donations.
7. Earned Income Tax Credit (EITC) and Other Refundable Credits
The EITC and other refundable credits (like the Child Tax Credit) are often targeted for audits due to the high potential for errors or fraudulent claims. While many claims are legitimate, the IRS dedicates resources to verify eligibility, especially for those with fluctuating incomes or complex family structures. Accurate record-keeping of dependents, income, and residency is crucial.
8. Math Errors and Discrepancies with Third-Party Reporting
This is a perennial red flag. Simple math errors or inconsistencies between what you report on your tax return and what third parties (employers, banks, investment firms) report to the IRS (on W-2s, 1099s, etc.) are easy for the IRS’s automated systems to spot. Always double-check your figures and ensure all income reported on forms like 1099-NEC, 1099-MISC, 1099-B, and W-2 is included in your return.
Proactive Strategies to Mitigate IRS Audit Risk
Understanding potential IRS audit triggers is the first step; taking proactive measures is the second, more critical one. Here’s how you can prepare for the evolving tax landscape and minimize your audit risk:
1. Meticulous Record-Keeping
This cannot be stressed enough. The best defense against an audit is comprehensive and organized documentation. Keep records for at least three years (the general statute of limitations for audits), but longer for certain items like real estate purchases or investments. This includes:
- All income statements (W-2s, 1099s).
- Receipts for all deductions claimed.
- Bank and credit card statements.
- Investment statements.
- Mileage logs, home office records, and business expense documentation.
- Documentation for charitable contributions, especially non-cash donations.
- Records for cryptocurrency transactions, including purchase dates, costs, and sale prices.
Consider digitalizing your records for easy access and backup.
2. Reconcile All Third-Party Reporting
Before filing your return, compare all W-2s, 1099s (various types), and K-1s you receive against what you plan to report. Ensure there are no discrepancies. If you receive a corrected form after filing, amend your return promptly.
3. Be Realistic and Avoid Aggressive Positions
While it’s important to claim all legitimate deductions and credits, avoid taking overly aggressive or questionable tax positions. If a deduction or income exclusion seems too good to be true, it likely is. The IRS is adept at identifying schemes and unusual claims that deviate significantly from industry norms or personal financial patterns.
4. Understand New Tax Laws and Reporting Requirements
Tax laws are constantly changing. Stay informed about new legislation, especially concerning areas like cryptocurrency, gig economy income, and international reporting. If you’re unsure, consult a qualified tax professional.
5. Accurately Report All Income
Every dollar of income, regardless of source, must be reported. This includes income from side hustles, freelance work, interest, dividends, capital gains, and foreign sources. The IRS’s data matching capabilities make it increasingly difficult to conceal income, and unreported income is a primary IRS audit trigger.
6. Seek Professional Tax Assistance
For complex tax situations, significant income, or if you’re involved in areas prone to scrutiny (like cryptocurrency or international investments), engaging a qualified tax professional (CPA, Enrolled Agent, or tax attorney) is highly recommended. They can help you navigate complex rules, ensure accurate reporting, and provide representation if an audit does occur.
7. Respond Promptly and Professionally to IRS Notices
If you receive a notice from the IRS, do not ignore it. Read it carefully, understand what it’s asking for, and respond promptly. Many notices are simply requests for clarification or minor adjustments that can be resolved without a full-blown audit. If you’re unsure how to respond, seek professional help.
8. Review Your Prior Year Returns
Periodically reviewing your past tax returns can help you identify any recurring issues or areas where you might be vulnerable. This self-assessment can be a valuable tool in proactive tax planning.
What Happens During an IRS Audit?
Should you receive an audit notice, understanding the process can help alleviate stress. IRS audits typically fall into three categories:
1. Correspondence Audits
These are the most common and least intrusive, handled entirely by mail. The IRS sends a letter requesting additional information or documentation to support specific items on your return. Responding accurately and completely is key.
2. Office Audits
For more complex issues, you might be asked to visit an IRS office. You’ll typically bring your records and discuss your return with an IRS agent. Having a tax professional accompany you or represent you is often advisable.
3. Field Audits
These are the most comprehensive, where an IRS agent visits your home, business, or the office of your tax professional. Field audits are usually reserved for businesses or individuals with very complex returns. Professional representation is almost always recommended for field audits.
During any audit, remember your taxpayer rights. You have the right to professional and courteous treatment, to privacy and confidentiality, to know why the IRS is asking for information, and to appeal IRS decisions.
The Importance of Staying Informed and Adaptable
The tax code is a living document, and the IRS’s enforcement priorities are constantly shifting. What might not have been a significant IRS audit trigger last year could become one in 2026. This dynamic environment underscores the importance of continuous learning and adaptability. Subscribing to reputable tax news sources, attending webinars, and maintaining an ongoing relationship with a knowledgeable tax advisor can help you stay current with the latest developments.
For instance, discussions around a potential national sales tax, changes to capital gains tax rates, or new regulations concerning digital assets are always on the horizon. Each of these could introduce new complexities and, consequently, new areas of IRS focus. Being prepared means not just reacting to current rules but anticipating future ones.
Moreover, the IRS’s use of data from state tax agencies, financial institutions, and even international bodies means that a holistic view of your finances is increasingly accessible to them. Therefore, ensuring consistency across all reported financial information, regardless of the reporting entity, is crucial.
Conclusion: Proactive Compliance is Your Best Defense
The prospect of new IRS audit triggers in 2026 and beyond highlights the need for US taxpayers to be more vigilant and proactive than ever before. The IRS is evolving, armed with more funding, better technology, and a clearer mandate to ensure compliance, particularly from high-income individuals and complex entities. By understanding the anticipated areas of scrutiny – from cryptocurrency to aggressive business deductions – and by implementing robust strategies for record-keeping, accurate reporting, and professional consultation, you can significantly reduce your audit risk.
Remember, the goal is not to avoid paying your fair share of taxes, but to ensure that your tax return accurately reflects your financial situation and complies with all applicable laws. Proactive compliance is your strongest defense against an IRS audit. Start preparing now, review your financial practices, and consult with tax professionals to ensure you are well-positioned for the tax landscape of 2026 and beyond. Taking these steps today will provide peace of mind and protect you from potential future complications with the IRS.