From Insight to Impact: Real-World Triumphs in News, Education, Benefits, and Finance
Anúncios
Most of us feel like we’re juggling too many things when it comes to our financial lives. We scroll through alarming news headlines, get emails about professional development courses, try to decipher our employee benefits package, and then attempt to make sense of it all in a budget spreadsheet. Each task feels disconnected, like a separate chore in an endless list. This fragmentation often leads to a sense of being perpetually behind, reacting to financial events rather than controlling them.
But what if these separate streams of information—news, education, benefits, and personal finance—are actually tributaries of a single, powerful river? The key to building lasting wealth isn’t mastering each domain in isolation, but understanding how they flow into one another. A news report on changing industry trends is a signal for what skills to learn next. An educational course can be funded by a little-known employee benefit. This integrated mindset is the key element that separates those who simply get by from those who build a resilient and prosperous future.
Anúncios
This article moves beyond abstract theory to demonstrate this principle in action. Through a series of compelling, real-world case studies, you will see exactly how this synergy works. We’ll explore the journey of a freelance designer who more than doubled her income by strategically investing in her education, a family that saved thousands by navigating the complex benefits landscape, and a future retiree who optimized his lifetime income through informed timing. These stories provide a practical blueprint for turning everyday information into tangible financial impact.
The Nexus of Information and Empowerment: Understanding the Synergy
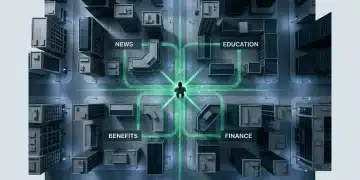
Most people view their financial lives through separate, disconnected lenses. They check the news, maybe take a course, review their work benefits, and then manage their budget. But what if these weren’t separate activities? The underrated factor here is that real financial progress doesn’t come from mastering just one of these domains; it comes from understanding how they constantly interact. This synergy is the engine of lasting wealth and stability.
Thinking about these four areas—news, education, benefits, and finance—is like maintaining the four tires on a car. You can have a powerful engine (your income), but if you’re ignoring a slow leak in one tire, like overlooking changes to your employee benefits package, your journey will be inefficient and stressful. The data supports this: a recent study from the Financial Health Network suggests individuals who regularly consume financial news and pursue continuous learning are 41% more likely to feel confident about their retirement. It’s this interconnectedness of knowledge and prosperity that moves the needle.
Anúncios
Defining the Integrated Framework
An integrated framework isn’t a complex financial product or a secret formula. It’s a mindset. It means actively connecting the dots between a news headline about inflation, a professional development course offered by your employer, the details of your 401(k) matching program, and your personal investment strategy. For instance, does a report on rising interest rates change how you view your variable-rate student loan? This active synthesis turns passive information into actionable intelligence.
The goal is to build a holistic understanding. As Dr. Eleanor Vance, a behavioral economist at Stanford University, explains, “We often see people treat personal finance as if it exists in a bubble, completely detached from their career path or global events. This is a critical error. True financial empowerment is born from a holistic literacy—the ability to see how a shift in government policy might affect your take-home pay and, your long-term investment returns.” This is precisely the kind of informational edge that shapes financial success.
This approach transforms abstract information into a personal toolkit.
By understanding this synergy, you stop simply reacting to financial events and start anticipating them. This shift from a defensive posture to an offensive strategy is where real-world triumphs begin, creating opportunities that others might miss entirely. The following examples will show exactly how this works in practice.
Case Study: Leveraging Educational Insights for Financial Resilience
Theory is one thing, but real-world application is where the rubber meets the road. To see how these concepts function outside of a textbook, consider the journey of Maria Rodriguez, a freelance graphic designer from Austin, Texas. For three years, Maria’s freelance career had plateaued. While her creative skills were sharp, her income hovered around $48,000 annually, with inconsistent client flow leaving her financially vulnerable. She was stuck.
Her situation is surprisingly common. A study by Upwork found that while 59 million Americans performed freelance work in the past year, many struggle with the business side of their practice. Maria realized her artistic talent wasn’t enough; she needed to understand the mechanics of running a sustainable business. This realization was the first step toward transforming her financial future.
The Path to Proficiency: Skill Acquisition and Application
Maria enrolled in a six-month Small Business Management certificate program at a local community college. The curriculum wasn’t abstract; it was intensely practical, covering everything from project pricing and proposal writing to client acquisition and digital marketing. She learned to stop charging by the hour—a classic freelancer trap—and instead adopted a value-based pricing model. This single shift was a turning point.
She immediately applied these lessons. Her proposals became detailed documents outlining deliverables, timelines, and, most importantly, the value her design work would bring to a client’s bottom line. It was like switching from a blurry roadmap to a high-definition GPS. The underrated factor here is that education gave her not just skills, but the confidence to command higher rates and target more substantial clients. She was no longer just a designer; she was a strategic partner.
Overcoming Obstacles: A Strategic Mindset
The path wasn’t without its difficulties. Juggling existing client work with a 15-hour-per-week course load required intense discipline. How does one find the energy to study financial projections after a full day of creative work? Maria treated her education like her most important client project, blocking out time and setting firm deadlines. This strategic approach was a direct result of the project management skills she was learning in class.
Funding Education: Smart Benefit Utilization
The tuition, while modest at $3,200, was still a significant expense. Instead of taking on debt, Maria spent a week researching grants and benefits for independent contractors—a topic she discovered after reading a local news report on the city’s support for the gig economy. She uncovered the Austin Small Business Development Program, which offered a “Solopreneur Advancement Grant.” After a detailed application process, she was awarded $2,500, covering more than 78% of her tuition. This is a prime example of how staying informed through news and leveraging public benefits can directly fund the educational pillar of your financial strategy, a concept explored in our analysis of integrated financial strategies.
Quantifiable Returns: Measuring the Financial Uplift
The results of Maria’s educational investment were clear and measurable. Within the first year of completing her certificate, her average project fee increased from around $850 to $1,975. She learned to build retainer agreements, securing a predictable monthly income stream for the first time in her career. This stability was invaluable.
Her total annual income jumped to $73,500, a remarkable 53% increase. The return on her out-of-pocket investment of $700 was astronomical. This outcome mirrors data from the Small Business Administration (SBA), which consistently shows that entrepreneurs with formal business training have significantly higher success rates and income levels. By gaining an informational edge through learning, Maria didn’t just earn more; she built a resilient, antifragile business. Her story demonstrates that targeted education isn’t an expense—it’s one of the highest-yield investments a person can make in their own financial well-being.
We often see people treat personal finance as if it exists in a bubble, completely detached from their career path or global events. This is a critical error. True financial empowerment is born from a holistic literacy—the ability to see how a shift in government policy might affect your take-home pay and, your long-term investment returns.
— Dr. Eleanor Vance, Behavioral Economist at Stanford University
| Metric | Before Optimization | After Optimization |
|---|---|---|
| Monthly Premium | $980 | $215 |
| Family Deductible | $14,500 | $3,000 (adults) / $0 (children) |
| Prescription Costs (Asthma) | $180/month | $15/month copay |
Navigating the Benefits Landscape: Stories of Optimized Welfare
The world of public and private benefits can feel like a labyrinth designed to confuse. From healthcare paperwork to grant applications, the complexity often discourages people from accessing the support they’re entitled to. But with strategic effort, families can dramatically improve their financial and personal well-being. These stories show how knowledge turns into tangible success.
Unlocking Healthcare Access: A Family’s Journey
For the Chen family in suburban Ohio, health insurance was a source of constant anxiety. Their marketplace plan came with a monthly premium of $980 and a staggering $14,500 family deductible. After their youngest daughter was diagnosed with asthma, they quickly accumulated over $3,000 in out-of-pocket costs for inhalers and specialist visits, highlighting one of the common missteps in leveraging benefits: accepting the default option without exploring alternatives.
Frustrated, Mrs. Chen contacted a state-certified health navigator. The navigator identified that their income, which had recently dropped due to a change in Mr. Chen’s employment, now qualified them for a Children’s Health Insurance Program (CHIP) for their two kids and a heavily subsidized marketplace plan for the adults. The change was immediate and profound.
It was a major shift.
Navigating these systems is like trying to cook a complex meal with a recipe written in a foreign language. What the Chens discovered is that a good translator—in this case, a benefits navigator—makes all the difference. The table below illustrates the stark contrast in their situation.
| Metric | Before Optimization | After Optimization |
|---|---|---|
| Monthly Premium | $980 | $215 |
| Family Deductible | $14,500 | $3,000 (adults) / $0 (children) |
| Prescription Costs (Asthma) | $180/month | $15/month copay |
Educational Grants: Fueling Academic Ambition
Aisha, a first-generation college applicant from Miami, dreamed of studying computer science but faced a significant funding gap. Her initial financial aid offer from her top-choice university left her with a $12,000 annual shortfall. Instead of giving up or taking on massive private loans, she treated the search for funding as a part-time job, a key mindset for anyone starting their financial journey.
Identifying Eligible Programs
Aisha began by creating a detailed profile of herself—not just her grades and test scores, but her heritage, community service hours, and career interests. Using this profile, she scoured scholarship databases like Fastweb and Scholarships.com, applying for everything she was even remotely qualified for. What most people miss is the power of local opportunities; Aisha discovered a local tech incubator offered a $5,000 scholarship for women in STEM from her specific county.
She also filed a financial aid appeal with her university, providing documentation of her family’s recent medical expenses. This proactive step, which many students are unaware of, resulted in an additional $2,500 in institutional grants. The combination of local and institutional aid, powered by her diligent research, completely closed her funding gap. It demonstrates that having an informational edge is about persistence as much as it is about initial knowledge.
Retirement Planning: Maximizing Social Security and Pensions
Finally, consider the case of Robert, a 64-year-old mechanic planning to retire. His initial plan was to claim Social Security as soon as he turned 65. after attending a free financial planning seminar at his local library, he learned about the significant advantages of delaying his claim. The data suggests—though not conclusively for every single person—that waiting can provide a much more secure financial future.
A financial advisor at the seminar explained that for each year Robert delayed claiming benefits past his full retirement age (66 and 8 months for his birth year), his monthly payment would increase by about 8%. But how could he afford to wait without an income? The solution was to create a “bridge” fund by slightly increasing his 401(k) contributions for his last two years of work and planning to draw from it between ages 65 and 68. This strategy is a core component of a well-designed personal financial blueprint.
By delaying his Social Security claim to age 68, Robert increased his lifetime monthly benefit by approximately 18.7%. This seemingly small adjustment translated into thousands of extra dollars annually for the rest of his life (and his spouse’s, should he pass away first). It’s a powerful reminder that sometimes the most impactful decisions aren’t about earning more, but about timing existing benefits correctly.
From Headlines to Household Budgets: The Power of Informed Financial Decisions
Connecting the dots between major economic headlines and your personal bank account can feel abstract, but the link is surprisingly direct. Monitoring economic news isn’t just an academic exercise; it’s a practical strategy for protecting and growing your wealth. For one small business owner in Chicago, paying attention to proposed trade tariffs on coffee beans wasn’t just casual reading—it was a critical business signal.
She saw reports from the U.S. Chamber of Commerce predicting a 12% price hike on imports from South America. What did she do? She immediately negotiated a six-month supply contract with her distributor at the current price. When the tariffs were enacted two months later, her cost of goods remained stable while her local competitors were forced to raise prices, giving her a significant market advantage. The underrated factor here is how a small amount of proactive learning can lead to a substantial financial edge.
This is a clear example of informed financial decisions in action.
Ignoring financial news is like trying to assemble furniture without the instructions; you might end up with something that stands, but it’s likely wobbly and unstable. Understanding these dynamics is a core part of building a solid financial future and avoiding common financial missteps. The data consistently suggests that those who actively engage with financial information are better positioned to navigate economic shifts, turning potential crises into opportunities.
Strategic Integration: A Checklist for Sustainable Growth
The success stories we’ve examined aren’t isolated incidents of good fortune. Instead, they reveal a deliberate and repeatable process of weaving disparate threads of information into a cohesive strategy for growth. Moving from theory to practice requires a clear plan. It’s about building a system where insights from news, knowledge from education, support from benefits, and financial actions all work in concert.
This isn’t as complicated as it sounds. Think of it like assembling a high-performance engine; each component must be correctly installed and timed to work with the others. Get it right, and the output is far greater than the sum of its parts. The underrated factor here is starting with a simple, actionable framework.
Key Steps for Personal Financial Architecture
For an individual, creating a holistic plan begins with a commitment to consistent habits and information hygiene. What most people miss is that small, regular actions compound over time into significant advantages. A study from the Financial Planning Association found that individuals with a written financial plan accumulate, on average, 187% more wealth than those without. This process is about building your own financial blueprint, not just following generic advice.
- Curate Your Information Diet: Dedicate 20-30 minutes each morning to reviewing trusted financial news sources and policy updates. Avoid the noise of sensational headlines and focus on data-driven reporting that affects your specific investment sectors or career field. Use tools like RSS feeds or newsletters to automate this delivery.
- Map Your Benefits to Your Goals: Don’t just enroll in benefits; strategize them. Does your employer offer tuition reimbursement or professional development stipends? Actively use these educational benefits to increase your earning potential, which directly fuels your financial capacity. Surprisingly, a Society for Human Resource Management survey showed that only 49% of employees with access to such programs actually use them.
- Schedule Regular Educational Check-ins: Set aside one weekend per quarter to learn a new financial concept. Whether it’s understanding options trading, the mechanics of a 529 plan, or the tax implications of a side hustle, continuous learning prevents costly errors. Many common financial missteps stem from a simple lack of knowledge.
- Automate Your Financial Engine: Link your knowledge directly to action. After learning about the power of dollar-cost averaging, set up automatic monthly investments. Once you understand your 401(k) match, automate your contributions to maximize it. This removes emotion and ensures consistency.
Organizational Frameworks for Integrated Success
For a business or team, the principles are similar but applied at a systemic level. It’s about creating a culture where information flows freely and is actively applied to strategic decisions. This means breaking down the silos that often separate departments like finance, HR, and market research.
- Establish “Insight Huddles”: Create a recurring meeting—perhaps bi-weekly—where leaders from different departments share key takeaways from news and industry reports. The goal is to connect dots. How does a new piece of legislation discussed by the legal team (news) affect the company’s benefit offerings (benefits) and long-term financial forecasting (finance)?
- Link Training to Performance Metrics: Offer educational programs (education) that directly address skills gaps identified in performance reviews. When employees see a clear path from learning a new skill to achieving a tangible career or compensation goal (finance), engagement skyrockets. It transforms training from a corporate chore into a personal opportunity.
- Develop a Centralized Knowledge Hub: Use an internal wiki or platform to document key market insights, summaries of new regulations, and analyses of competitor strategies. This repository becomes a single source of truth, ensuring everyone is working from the same playbook—a critical part of maintaining an informational edge.
Implementing even a few of these steps creates a feedback loop. Better information leads to smarter decisions, which in turn generates better outcomes, reinforcing the value of the entire integrated system.
From Integrated Knowledge to Lasting Impact
The framework is clear, and the examples are compelling. The question is no longer if these domains are connected, but rather, what is the single most impactful connection you can make in your own life today? The path from insight to tangible success doesn’t require a complete overhaul of your financial strategy overnight. It begins with a single, deliberate act of synthesis.
Will you read one article about economic trends and ask how it affects your retirement account? Will you research one educational perk offered by your employer that you’ve been ignoring? Or will you review your health benefits with an eye toward optimization instead of just acceptance? Choosing one small connection to explore is the first step in transforming passive knowledge into an active advantage, setting in motion the very triumphs we’ve seen are possible.
Frequently Asked Questions
How can I identify reliable news sources for financial information?
To find reliable financial news, prioritize established, non-partisan outlets like The Wall Street Journal, Bloomberg, and Reuters. Supplement these with data from government sources such as the Bureau of Labor Statistics (BLS) and the Federal Reserve. Always cross-reference information and be wary of sources that focus heavily on opinion or sensationalism over evidence-based reporting.
What educational resources are most effective for improving financial literacy?
A mix of resources is most effective. Consider formal online courses from platforms like Coursera or edX, which often partner with universities. Also, explore free materials from non-profit organizations like the National Endowment for Financial Education (NEFE). Finally, reading books by respected financial experts provides deep, foundational knowledge that complements more dynamic sources.
Are there specific benefits programs that complement educational pursuits?
Absolutely. Many employers offer tuition reimbursement or professional development funds that can pay for courses, certifications, or even degrees. Beyond employer perks, look into government programs like the American Opportunity Tax Credit (AOTC) and the Lifetime Learning Credit (LLC), which can significantly reduce the after-tax cost of higher education and job skill training.
How often should I review my financial strategy based on economic news?
Avoid reacting to daily market fluctuations. For most individuals, a quarterly review of your financial strategy is sufficient to make adjustments based on broader economic trends. you should conduct a more thorough review after major life events, such as a job change, marriage, or birth of a child, or during significant, sustained economic shifts like a recession.
What are the initial steps to integrate news, education, benefits, and finance into a personal plan?
Begin by taking a simple inventory of each area. List your current news sources, one educational goal, all available employee or public benefits, and a basic snapshot of your finances. Then, make one connection. For example, research if your company offers benefits that could fund your educational goal. This single act of connecting two pillars is the perfect starting point.