Maximizing Your Education Benefits: Understanding the 2026 Tax Credits for Lifelong Learning in the U.S.
Anúncios
Education is a cornerstone of personal and professional growth, and in the United States, the government offers various incentives to help offset its often substantial costs. Among the most significant of these are education tax credits. As we look ahead to 2026, understanding the nuances of these credits becomes paramount for students, parents, and lifelong learners alike. This comprehensive guide will delve into the 2026 Education Tax Credits, exploring what’s available, who qualifies, and how you can strategically leverage these benefits to maximize your financial relief.
The landscape of tax law is ever-evolving, and staying informed about potential changes and enduring provisions is crucial. Whether you’re pursuing a traditional four-year degree, a vocational certificate, or simply taking courses for professional development, the U.S. tax code provides avenues for reducing your educational expenses. This article aims to demystify the process, offering clear, actionable insights into the key education tax credits you should be aware of for the 2026 tax year.
We’ll cover the primary federal education tax credits – the American Opportunity Tax Credit (AOTC) and the Lifetime Learning Credit (LLC) – detailing their eligibility requirements, maximum benefits, and the types of educational expenses they cover. Furthermore, we’ll discuss important considerations, such as income limitations, filing requirements, and how these credits interact with other forms of financial aid. Our goal is to equip you with the knowledge needed to confidently navigate your educational funding options and ensure you don’t leave any money on the table.
Anúncios
The Foundation: Understanding Federal Education Tax Credits
Before diving into the specifics of 2026 Education Tax Credits, it’s essential to grasp the fundamental differences between tax credits and tax deductions. While both can reduce your tax liability, they do so in distinct ways. A tax deduction reduces your taxable income, thereby lowering the amount of tax you owe. A tax credit, on the other hand, directly reduces the amount of tax you owe, dollar for dollar. This makes tax credits generally more valuable than deductions of the same amount.
For educational expenses, the U.S. government primarily offers two significant tax credits: the American Opportunity Tax Credit (AOTC) and the Lifetime Learning Credit (LLC). Each credit serves a slightly different purpose and has unique eligibility criteria, making it important to understand which one best fits your situation. It’s crucial to note that you generally cannot claim both credits for the same student in the same tax year, so careful consideration and calculation are necessary.
The American Opportunity Tax Credit (AOTC)
The AOTC is arguably the most generous education tax credit available, designed to help students cover the costs of higher education during their first four years of postsecondary schooling. For the 2026 tax year, while specific dollar amounts are subject to inflation adjustments, the core structure of the AOTC is expected to remain consistent with previous years. This credit offers significant financial relief for eligible students and families.
Eligibility for AOTC:
- Enrollment: The student must be pursuing a degree or other recognized educational credential.
- Enrollment Status: The student must be enrolled at least half-time for at least one academic period beginning in the tax year.
- Academic Level: The student must be in their first four years of higher education (meaning, they haven’t completed four years of postsecondary education before the beginning of the tax year).
- Prior AOTC Claims: The AOTC can only be claimed for a student for four tax years.
- Felony Drug Convictions: The student must not have a felony drug conviction on their record at the end of the tax year.
What Expenses Does AOTC Cover?
The AOTC is applicable to a range of qualified education expenses, including:
- Tuition and fees required for enrollment or attendance.
- Course-related books, supplies, and equipment that are required for enrollment or attendance, even if not purchased directly from the educational institution.
Importantly, living expenses, transportation, and similar personal expenses are generally not considered qualified education expenses for the AOTC.
Maximum Benefit of AOTC:
The AOTC provides a maximum annual credit of $2,500 per eligible student. What makes this credit particularly appealing is that up to 40% ($1,000) of the credit is refundable. This means that if the credit reduces your tax liability to $0, you could still receive up to $1,000 back as a tax refund, even if you paid no tax. This refundable portion can be a lifesaver for lower-income individuals and families.
The Lifetime Learning Credit (LLC)
The Lifetime Learning Credit (LLC) is designed for a broader range of educational pursuits, making it ideal for graduate students, those pursuing professional development, or individuals taking courses to acquire new job skills. Unlike the AOTC, there’s no limit on the number of years you can claim the LLC, and it doesn’t require the student to be pursuing a degree or to be enrolled at least half-time. This flexibility makes it a valuable resource for lifelong learners.
Eligibility for LLC:
- Enrollment: The student must be enrolled in an eligible educational institution.
- Course Purpose: The student must be taking courses towards a degree, or to acquire job skills.
- Enrollment Status: No minimum enrollment status is required; even a single course can qualify.
- Felony Drug Convictions: There is no restriction regarding felony drug convictions for the LLC.
What Expenses Does LLC Cover?
The LLC covers qualified education expenses, which include:
- Tuition and fees required for enrollment or attendance.
- Course-related books, supplies, and equipment required for enrollment or attendance, but only if they must be purchased from the educational institution as a condition of enrollment or attendance. This is a key difference from the AOTC.
Similar to the AOTC, living expenses, transportation, and similar personal expenses are not considered qualified for the LLC.
Maximum Benefit of LLC:
The LLC provides a maximum annual credit of $2,000 per tax return. This is calculated as 20% of the first $10,000 in qualified education expenses, up to a maximum of $2,000. It’s important to note that the LLC is non-refundable, meaning it can reduce your tax liability to $0, but you won’t receive any portion of the credit back as a refund.
Key Changes and Considerations for 2026 Education Tax Credits
While the fundamental structure of the AOTC and LLC is expected to remain consistent, taxpayers should always be aware of potential adjustments, particularly regarding income limitations and phase-out ranges due to inflation. The IRS typically announces these adjustments annually. For 2026 Education Tax Credits, it’s prudent to consult the most current IRS publications or a qualified tax professional as the tax year approaches.
Income Limitations and Phase-Outs:
Both the AOTC and LLC are subject to income limitations. This means that if your Modified Adjusted Gross Income (MAGI) exceeds certain thresholds, the amount of credit you can claim will be reduced (phased out) or eliminated entirely. These thresholds are adjusted periodically for inflation. For the 2026 tax year, taxpayers should look for updated MAGI limits. Generally, for the AOTC, the phase-out begins for single filers and married couples filing jointly at specific MAGI levels, with the credit completely phased out at higher MAGI levels. The LLC has similar, though often different, income thresholds.
Claiming the Credits: Who Can Claim?
The question of who can claim the education tax credit – the student or the parent – depends on whether the student is claimed as a dependent on someone else’s tax return. If a student is claimed as a dependent, only the person claiming the student as a dependent (usually a parent) can claim the education credit. If the student is not claimed as a dependent, they can claim the credit themselves. This is a critical distinction that can impact which credit is chosen and how it’s maximized.
Furthermore, if you are married and filing separately, you generally cannot claim either the AOTC or the LLC.
Form 1098-T: Your Essential Document
To claim any education tax credit, you will need Form 1098-T, Tuition Statement, which is issued by eligible educational institutions to students. This form reports the amount of qualified tuition and related expenses billed or paid during the calendar year. It’s your primary documentation for substantiating your claims for 2026 Education Tax Credits. Ensure you receive this form from your educational institution and keep it with your tax records.
Strategic Planning to Maximize Your 2026 Education Tax Credits
Maximizing your education tax credits requires careful planning and a thorough understanding of the rules. Here are several strategies and scenarios to consider:
Choosing Between AOTC and LLC:
As mentioned, you generally cannot claim both credits for the same student in the same tax year. Therefore, you must choose the credit that provides the greatest benefit. The AOTC is often more advantageous for undergraduate students in their first four years of study due to its higher maximum credit and refundable portion. The LLC is typically better for graduate students, those taking a few courses, or those who have already claimed the AOTC for four years. Always calculate both to see which yields a better outcome.
Coordination with Other Financial Aid:
Education tax credits can interact with other forms of financial aid, such as scholarships, grants, and fellowships. Generally, any tax-free educational assistance (like Pell Grants or scholarships that exceed qualified educational expenses) reduces the amount of qualified expenses you can use to calculate your credit. However, taxable scholarships or grants do not reduce qualified expenses. Understanding this interaction is key to accurately calculating your eligible expenses for 2026 Education Tax Credits.
Timing of Payments:
The timing of when you pay for qualified education expenses can sometimes impact which tax year you can claim the credit. Expenses paid in one year for an academic period that begins in the first three months of the next year can often be used for the current tax year’s credit. This flexibility can be useful for tax planning, especially near year-end.
Record Keeping:
Meticulous record-keeping is vital. Keep all receipts, invoices, and statements related to qualified education expenses, including tuition bills, book purchases, and any other eligible costs. While Form 1098-T is crucial, it may not include all qualified expenses (e.g., books purchased from a third party for AOTC). Having detailed records will support your claim in case of an IRS inquiry.
What if Your Income is Too High?
If your income exceeds the phase-out limits for both credits, you may not be able to claim them. In such cases, exploring other education-related tax benefits, such as the student loan interest deduction (if applicable), might be an alternative. However, the student loan interest deduction is a deduction, not a credit, so its impact on your tax liability will be less direct.
Beyond the Credits: Other Education-Related Tax Benefits
While the AOTC and LLC are the primary tax credits for education, it’s worth noting other potential tax benefits that can help alleviate educational costs. These might include:
Student Loan Interest Deduction:
You may be able to deduct the amount of interest you paid during the year on a qualified student loan, up to a maximum of $2,500. This is an above-the-line deduction, meaning it reduces your adjusted gross income (AGI) and you don’t need to itemize to claim it. This deduction is subject to income limitations.
Employer-Provided Educational Assistance:
If your employer provides educational assistance, up to a certain amount (e.g., $5,250 for 2026, subject to inflation adjustments) can be excluded from your taxable income. This applies to both undergraduate and graduate courses and can cover tuition, fees, books, supplies, and equipment.
Savings Plans for Education (529 Plans and Coverdell ESAs):
While not tax credits, 529 plans and Coverdell Education Savings Accounts (ESAs) offer tax-advantaged ways to save for education. Contributions are made with after-tax dollars, but earnings grow tax-free, and withdrawals are tax-free if used for qualified education expenses. These plans are excellent long-term savings vehicles for future educational costs.
Staying Informed for 2026 and Beyond
The tax code is dynamic, and provisions related to education benefits can be subject to legislative changes. While this guide provides a solid understanding of the expected 2026 Education Tax Credits, it is always recommended to:
- Consult IRS Publications: Regularly check IRS Publication 970, Tax Benefits for Education, for the most up-to-date and detailed information.
- Seek Professional Advice: For complex situations or significant educational expenses, consulting a qualified tax professional can ensure you are maximizing all available benefits and complying with all tax laws.
- Monitor Legislative Updates: Keep an eye on news from the IRS and tax authorities for any proposed or enacted changes that could impact education tax credits in the future.
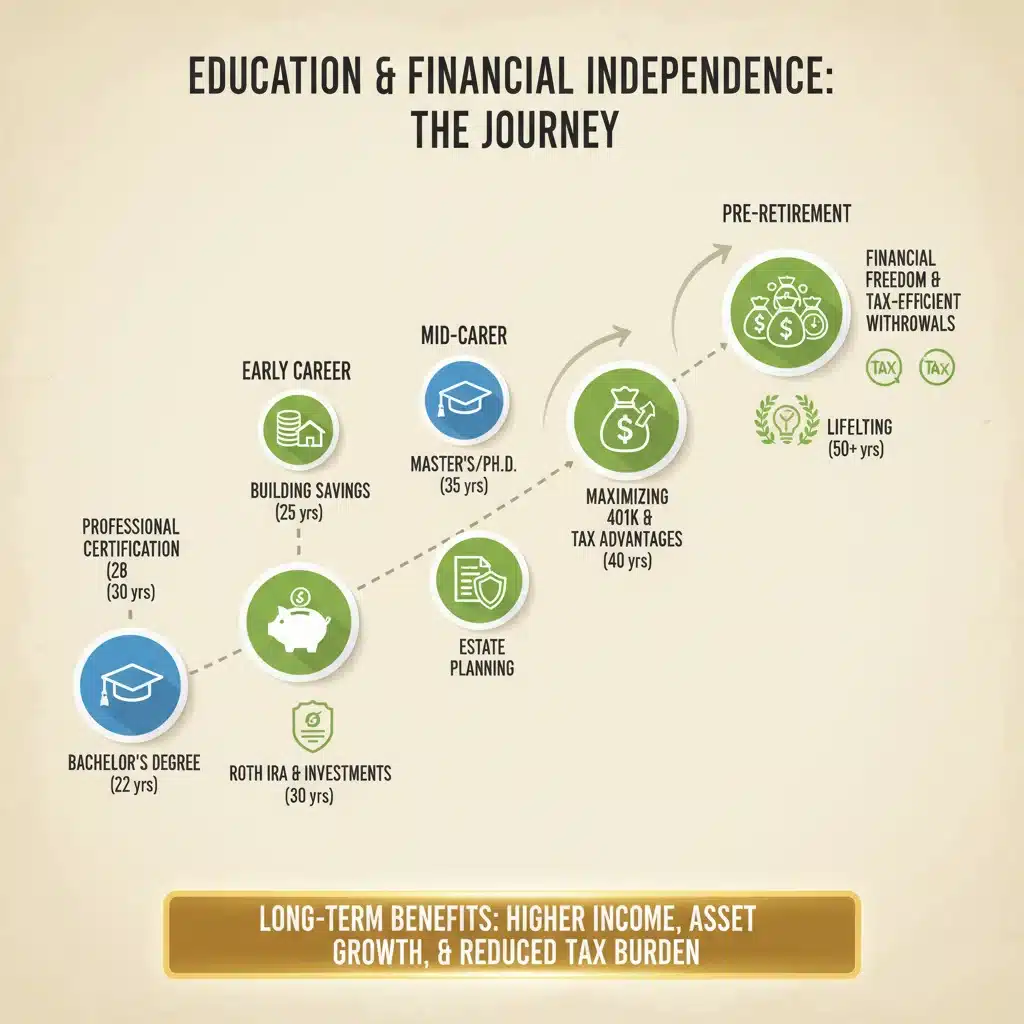
Conclusion: Empowering Your Educational Journey with 2026 Education Tax Credits
Investing in education is an investment in your future, and the U.S. tax system offers valuable incentives to support this endeavor. By thoroughly understanding the 2026 Education Tax Credits, specifically the American Opportunity Tax Credit and the Lifetime Learning Credit, you can significantly reduce the financial burden of pursuing knowledge and skills. Careful planning, meticulous record-keeping, and an awareness of eligibility requirements and income limitations are your best tools for maximizing these benefits.
Whether you are a student embarking on your college journey, a professional seeking to enhance your career through continuing education, or a parent supporting your child’s academic aspirations, these tax credits provide a tangible way to make education more affordable and accessible. Don’t underestimate the power of these tax savings; they can free up funds for other essential needs or allow you to invest further in your educational development.
As you prepare for the 2026 tax season, take the time to review your educational expenses and eligibility for these crucial credits. Leverage the information provided here as a starting point, and don’t hesitate to seek expert guidance to ensure you are taking full advantage of every opportunity to reduce your tax liability. Your commitment to lifelong learning can be financially rewarding, thanks to the robust framework of education tax benefits available.